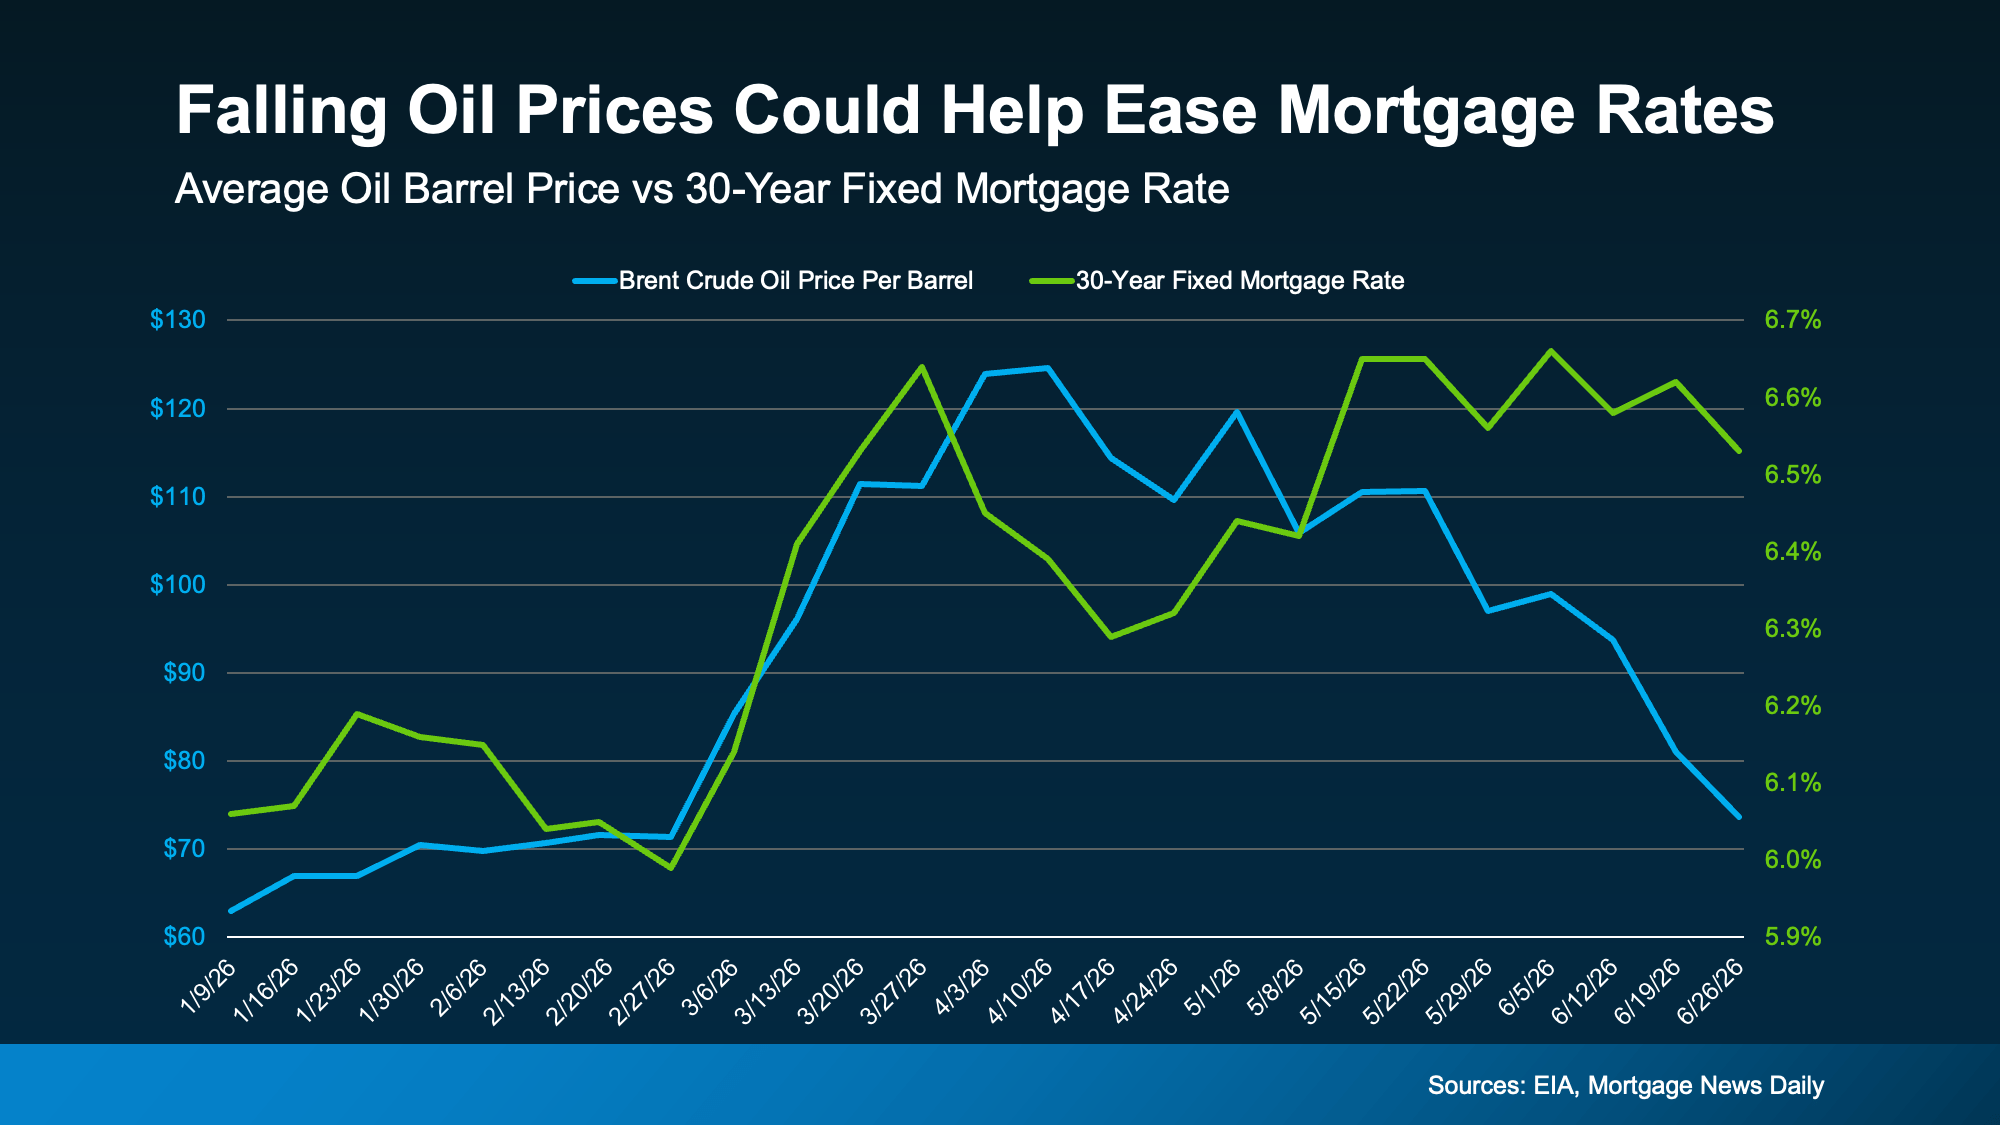Real Estate Information Archive

Blog

Displaying blog entries 11-20 of 568

More Homes and Cabins, Better Prices on Mt. Hood!

by Liz Warren

More Homes, Better Prices: A Buyer’s Summer


If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.

In many places, both sticking points are letting up this summer, with lower asking prices and more homes for sale. Let’s look at the trends, and what they mean for your search.

Sellers Are Pricing To Attract Buyers

According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 under what it was the year before (see graph below):
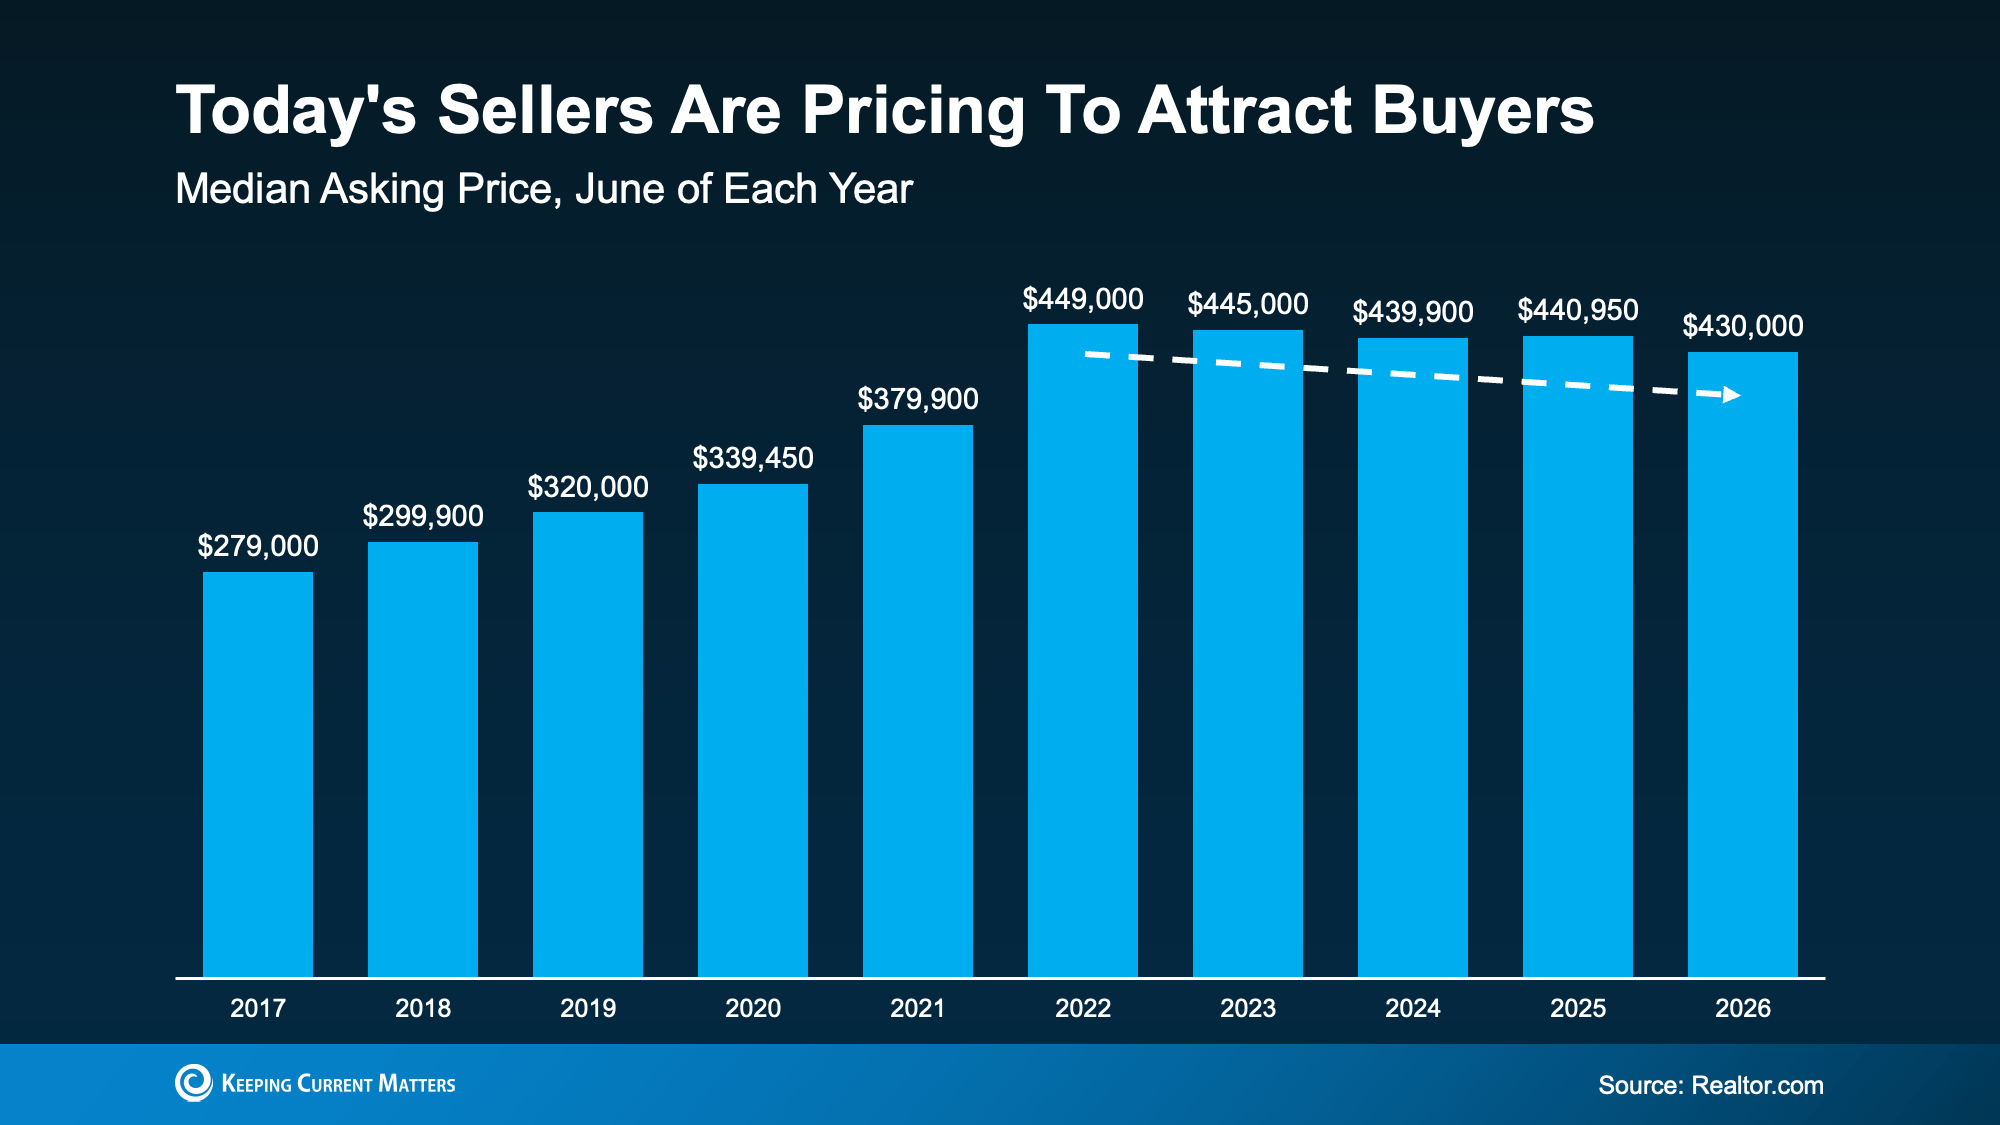
a graph of sales

That’s the eighth month in a row that the typical asking price has dipped below where they were the previous year, according to the same Realtor.com report.

And while falling prices can sound worrying, this isn’t a sign of an impending crash. We’re talking about asking prices, not sold prices. This is a sign that today’s sellers are meeting the market where it is and pricing to draw buyers. And that’s actually something normal we’d expect from the market. As Danielle Hale, Chief Economist at Realtor.com, puts it:

“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”

Asking prices were never going to climb forever – now they're just settling closer to what buyers can actually pay. That signals a healthier market, and sellers re-adjusting their expectations. 

More Homes Are Available Now

If you’ve spent the past few years watching homes disappear before you could even schedule a tour, this is for you.

Supply is starting to catch up. According to Realtor.com, the number of homes listed for sale in June was the highest June number we’ve seen in three years (see graph below):
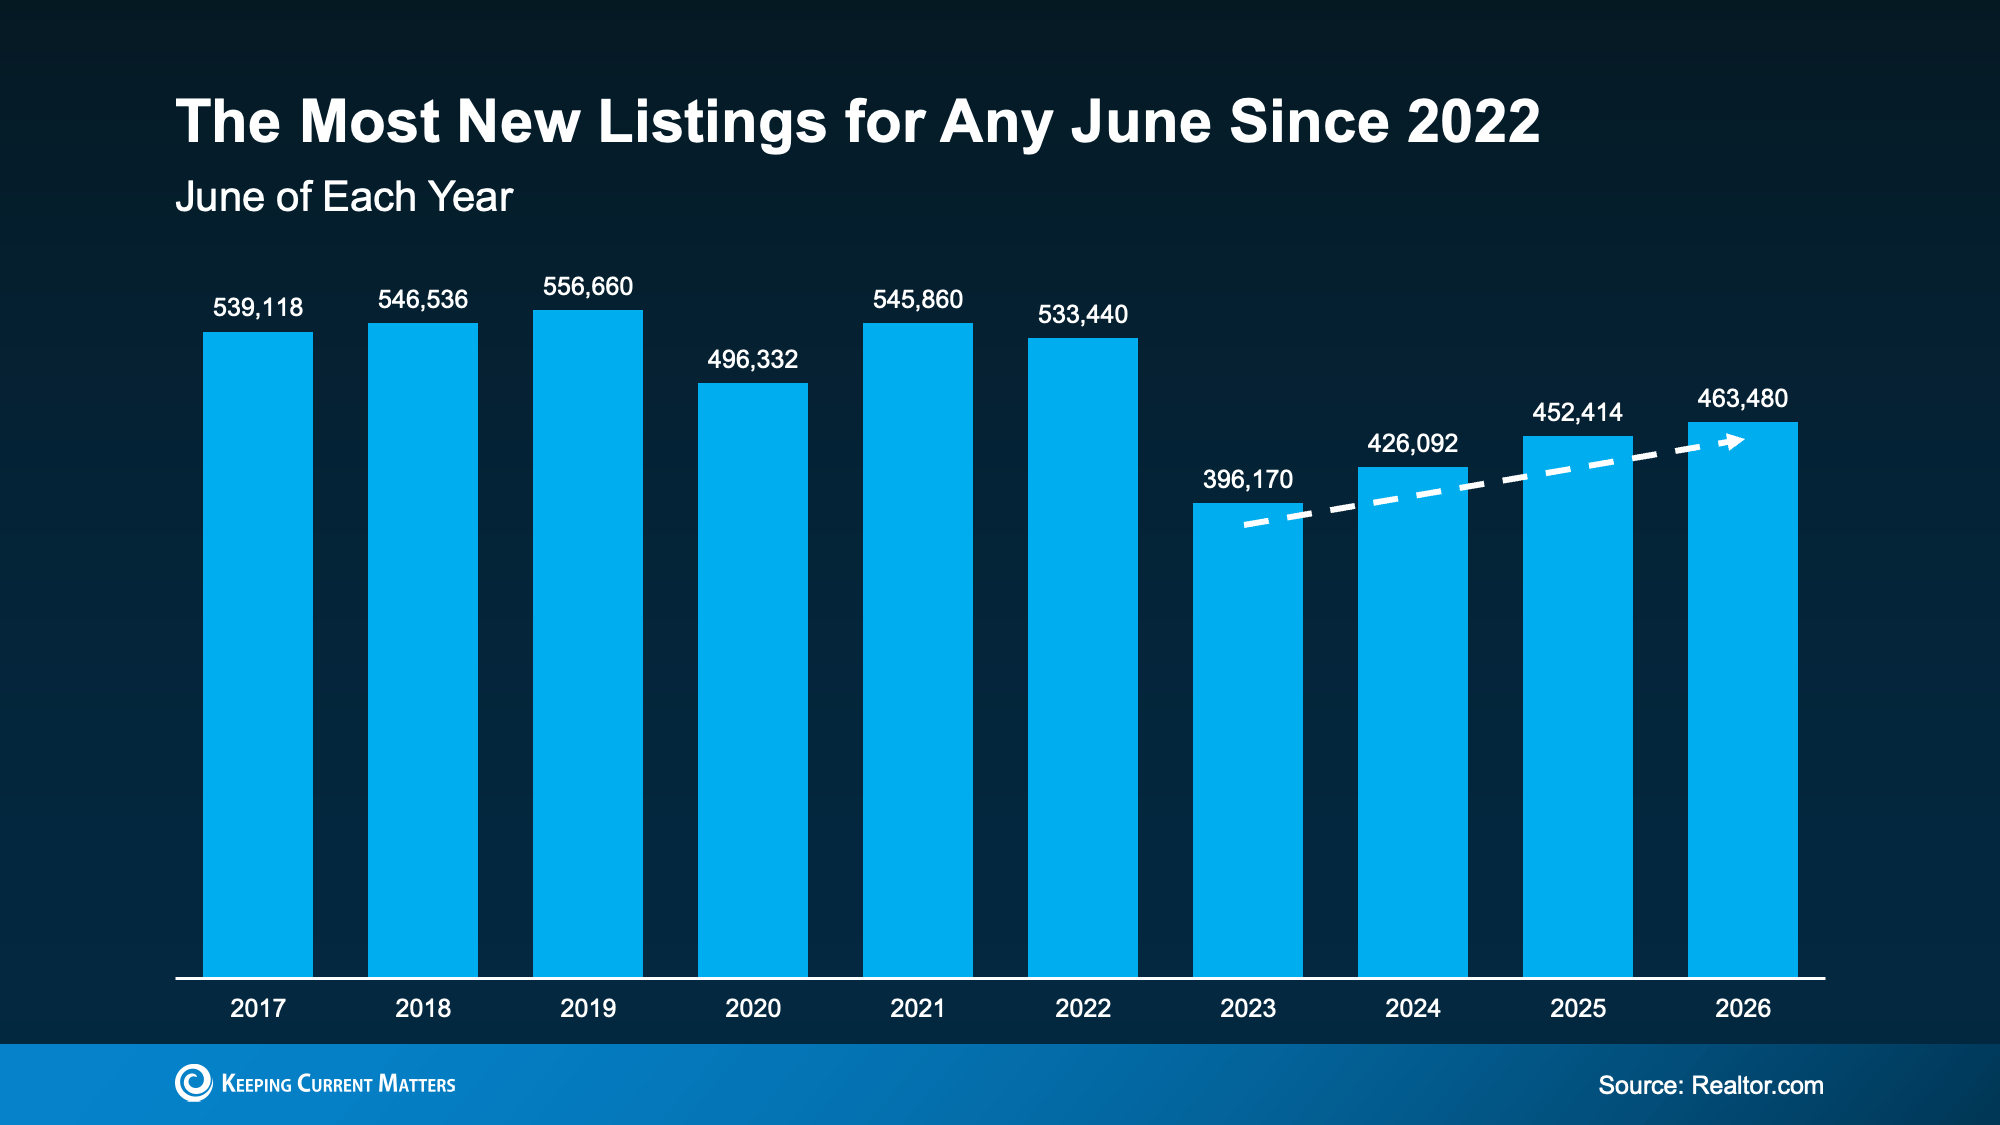
a graph with numbers and a number of blue bars

This means more options for you and less competition for each one.

Now, supply is not back to normal everywhere. As you can see, we’re still down from where we were back in 2017-2019. But in many places, it’s better than it’s been in a while. Here’s how that helps you.

You don’t have to rush an offer just to stay in the running, and you have better odds of finding and landing the right home, not just the one that’s available. Plus, you’ll have more room to negotiate, so you’re searching from a stronger position than buyers had even a year ago.

Why This Is Encouraging if You’re Buying Your First Home

For first-time buyers looking for lower-priced homes, these trends line up especially well. Mischa Fisher, Chief Economist at Zillow, explains:

“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”

So, if you’re searching for your first place or your next house, there's a little more to choose from and a little more give on price.

Bottom Line

If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.

Ready to see what’s available here? Let’s connect.
Projections Nationally for Home Sales for the Rest of 2026

by Liz Warren

What To Expect from the Housing Market in the Second Half of 2026


If the first half of this year has left you feeling stuck, you're not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.

That's why so many people are asking the same question: Will the second half of the year be any better for the housing market?

While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here's what to watch.

Mortgage Rates Could Be Near a Turning Point 

One of the biggest reasons mortgage rates haven't come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?

Oil prices have already started coming back down.

That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.

Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:

a graph showing the price of a mortgage rate

It's too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.

And that’s good news for anyone thinking about moving. The first half of the year tested everyone's patience. The second half may finally reward it.

Home Prices Could Pick Back Up

A lot of people want home prices to fall too. But that’s not what most forecasts show.

While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.

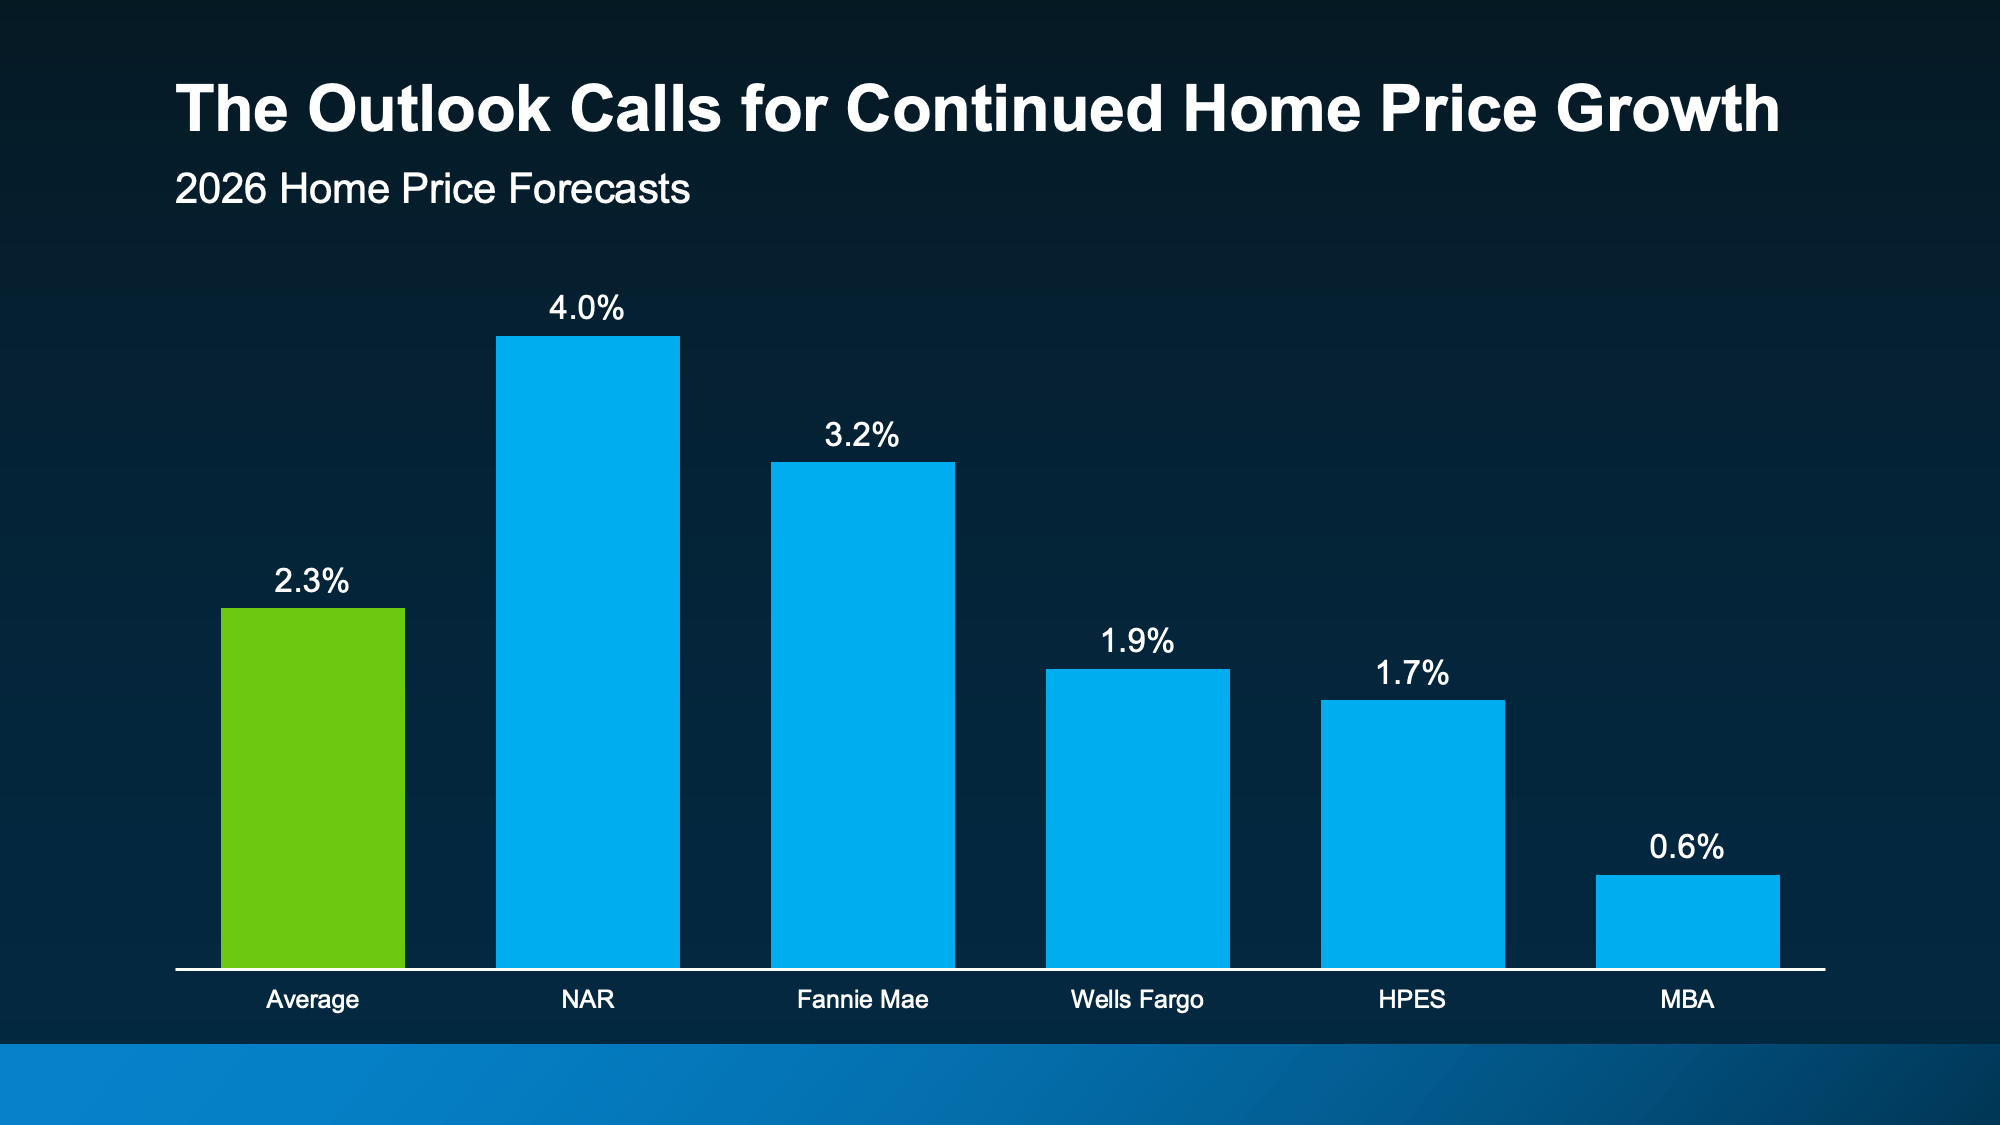
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):

a graph of blue rectangular objects

What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.

Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.

Here’s why that’s possible.

The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.

That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.

More Homes Are Expected To Sell

If you've been wondering why the housing market has felt quieter lately, you're not imagining it. Home sales have been slower than many experts expected. But that doesn't mean people have stopped wanting to move.

A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon. 

If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.” 

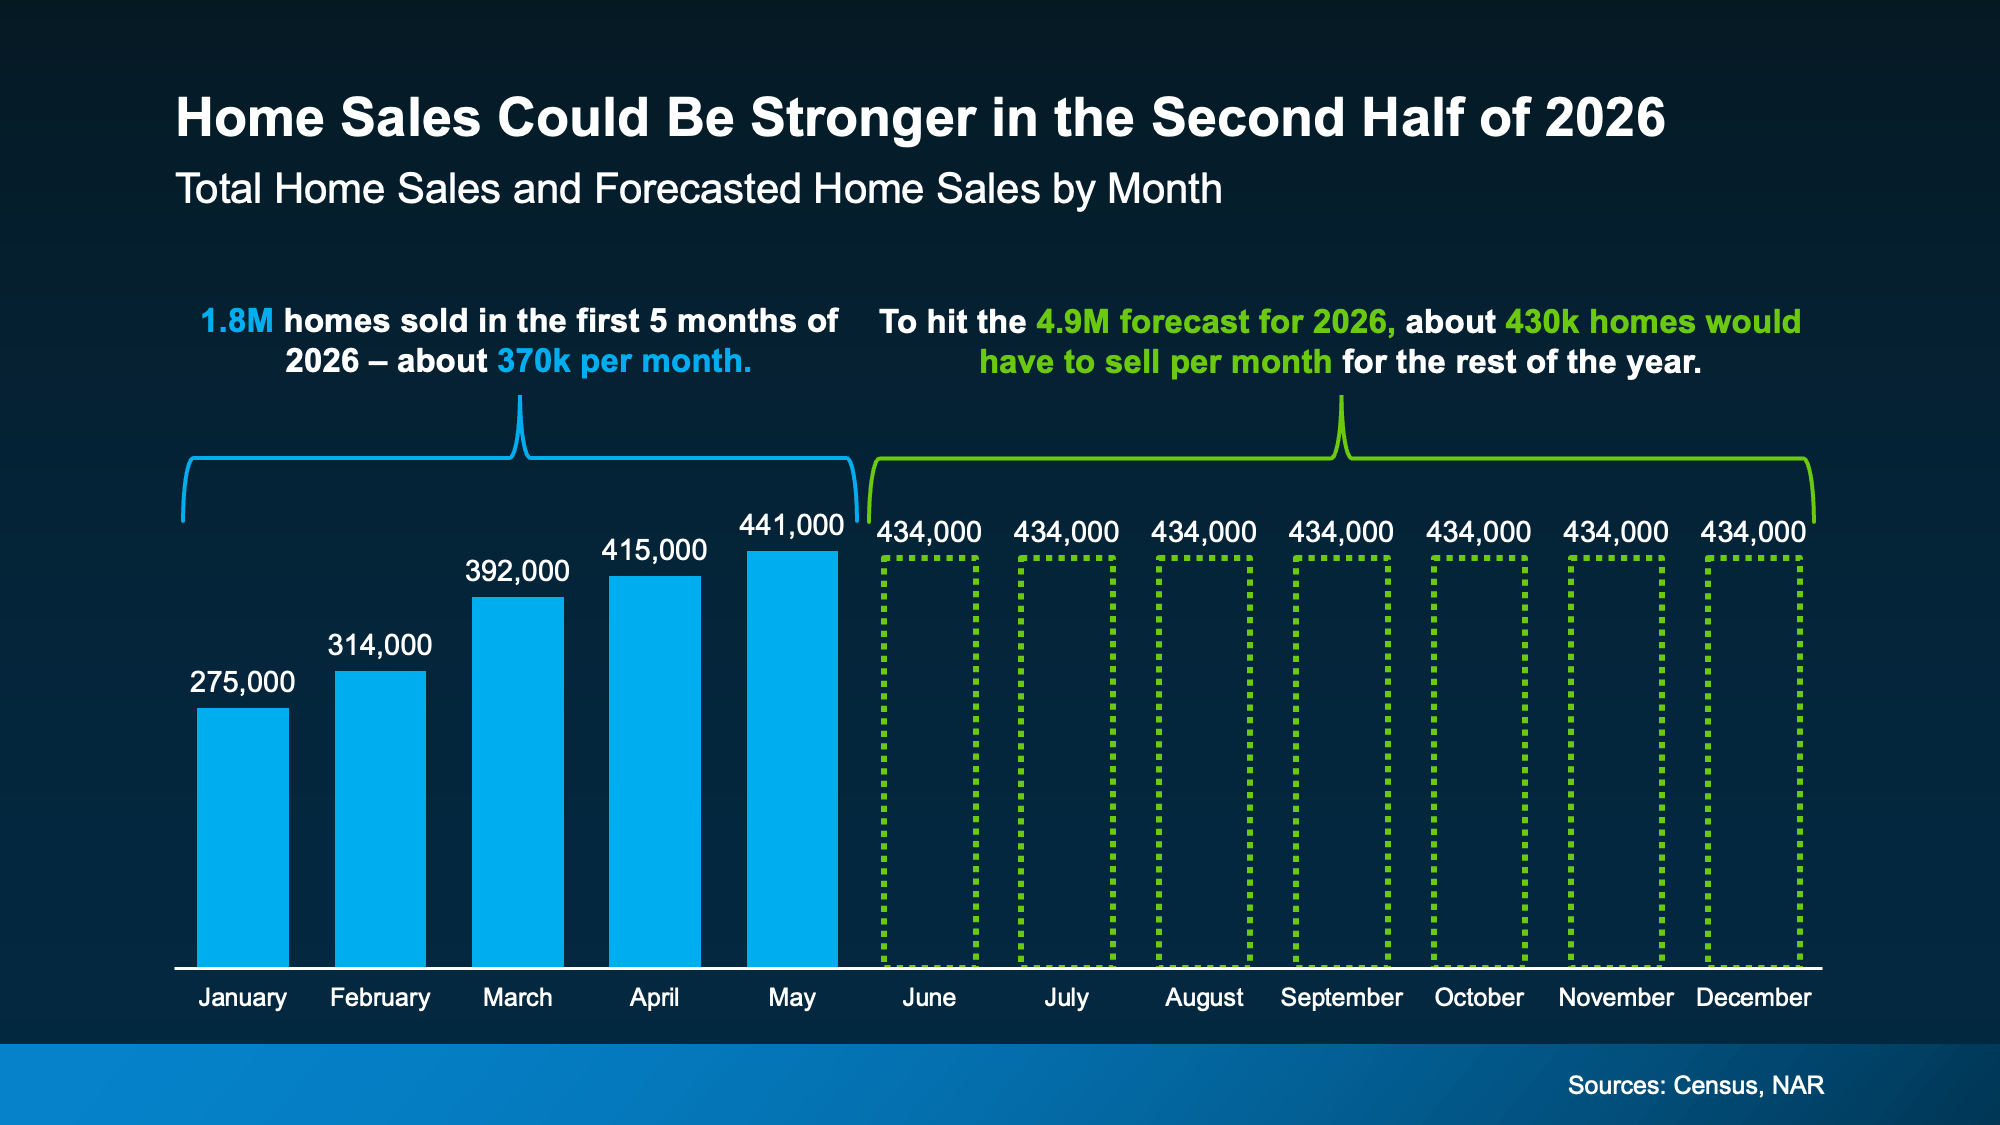
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):

a graph of sales and statistics

In fact, each month for the rest of 2026 would have to come close to matching the best month we've had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.

More people will finally make their move happen – and you've got the chance to be one of them.

Bottom Line

The second half of the year probably won't be perfect. But it could be better.

Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you've been waiting for signs of progress, this is it.

If you want to understand what these forecasts mean for your plans and what’s happening in our local market, let’s connect.

Only 5% of Sellers Sell Without an Agent

by Liz Warren

More Sellers Are Taking Their Homes off the Market

by Liz Warren

More Sellers Are Taking Their Homes off the Market. Here’s What You Need To Know.


You may be hearing that a near-record number of homeowners are pulling their houses off the market. And if that headline has you thinking, “Wait… is something bad about to happen?” You’re not alone.

Because when people start stepping to the sidelines, it sounds like a warning sign that something’s coming – or that they realize something you don’t know.

Here’s the thing. This trend gets spun like it means the market is about to crash. But the data tells a more practical story.

What the Numbers Actually Say

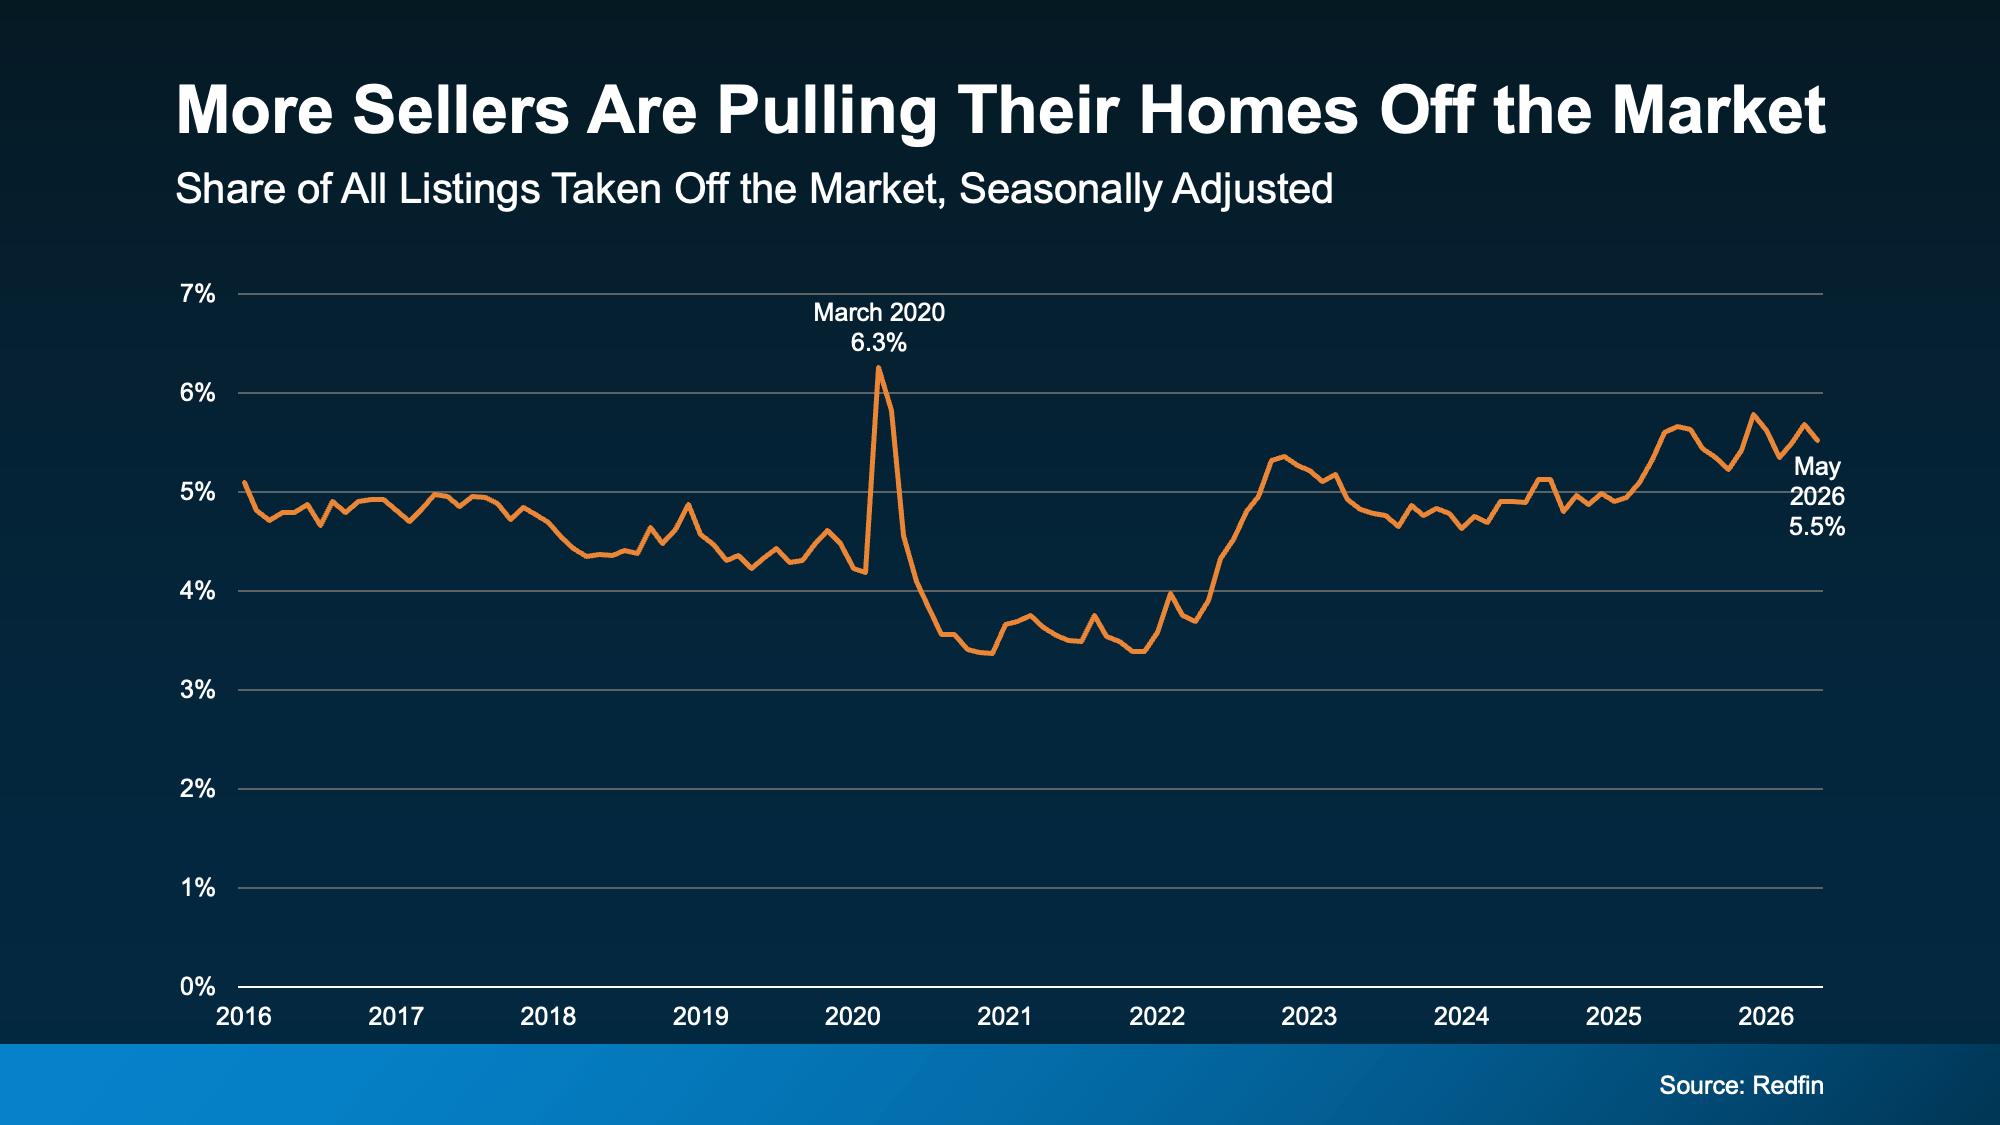
According to the latest data from Redfin, 5.5% of all listings were taken off the market in May. And it’s true that’s almost the highest it’s been since back in March 2020 (see graph below): 

a graph showing the price of a home

That can sound scary. But a lot of the fear comes from how this story gets told. “A near record number of sellers are pulling their listings” makes a great clickbait headline – and that sort of thing spreads fast, especially online. But sellers pull a house off the market for plenty of reasons that have nothing to do with a crash.

Redfin points to four main forces driving this trend:

  • Homes are taking longer to sell. When the pace slows down, some sellers get frustrated and decide to hold off.

  • The number of homes for sale is rising faster than demand. That means buyers have more options. And sellers who don’t price or prep right may not get many eyes on their house.

  • Some sellers still have pandemic-era price expectations. A price that would’ve worked a couple years ago may not match what today’s buyers will pay.

  • Economic uncertainty is making both buyers and sellers cautious. Buyers pause. Sellers second-guess. And that has an impact on overall sales volume and pace.

Notice what’s missing from that list? There isn’t a single mention of an impending market crash or price collapse.

This is about a shifting pace, more competition, and sellers deciding how they want to respond.

One Detail Most Headlines Leave Out

Want more peace of mind that this isn’t a crash? This next stat delivers. Yes, more sellers are taking their homes off the market. But Redfin also shows something you're not going to see in social posts...

The number of re-listings is growing too.  

While more sellers are pulling their listings, more are also deciding to give selling a second shot too. This is pretty much the highest re-listings have been since the pandemic hit.

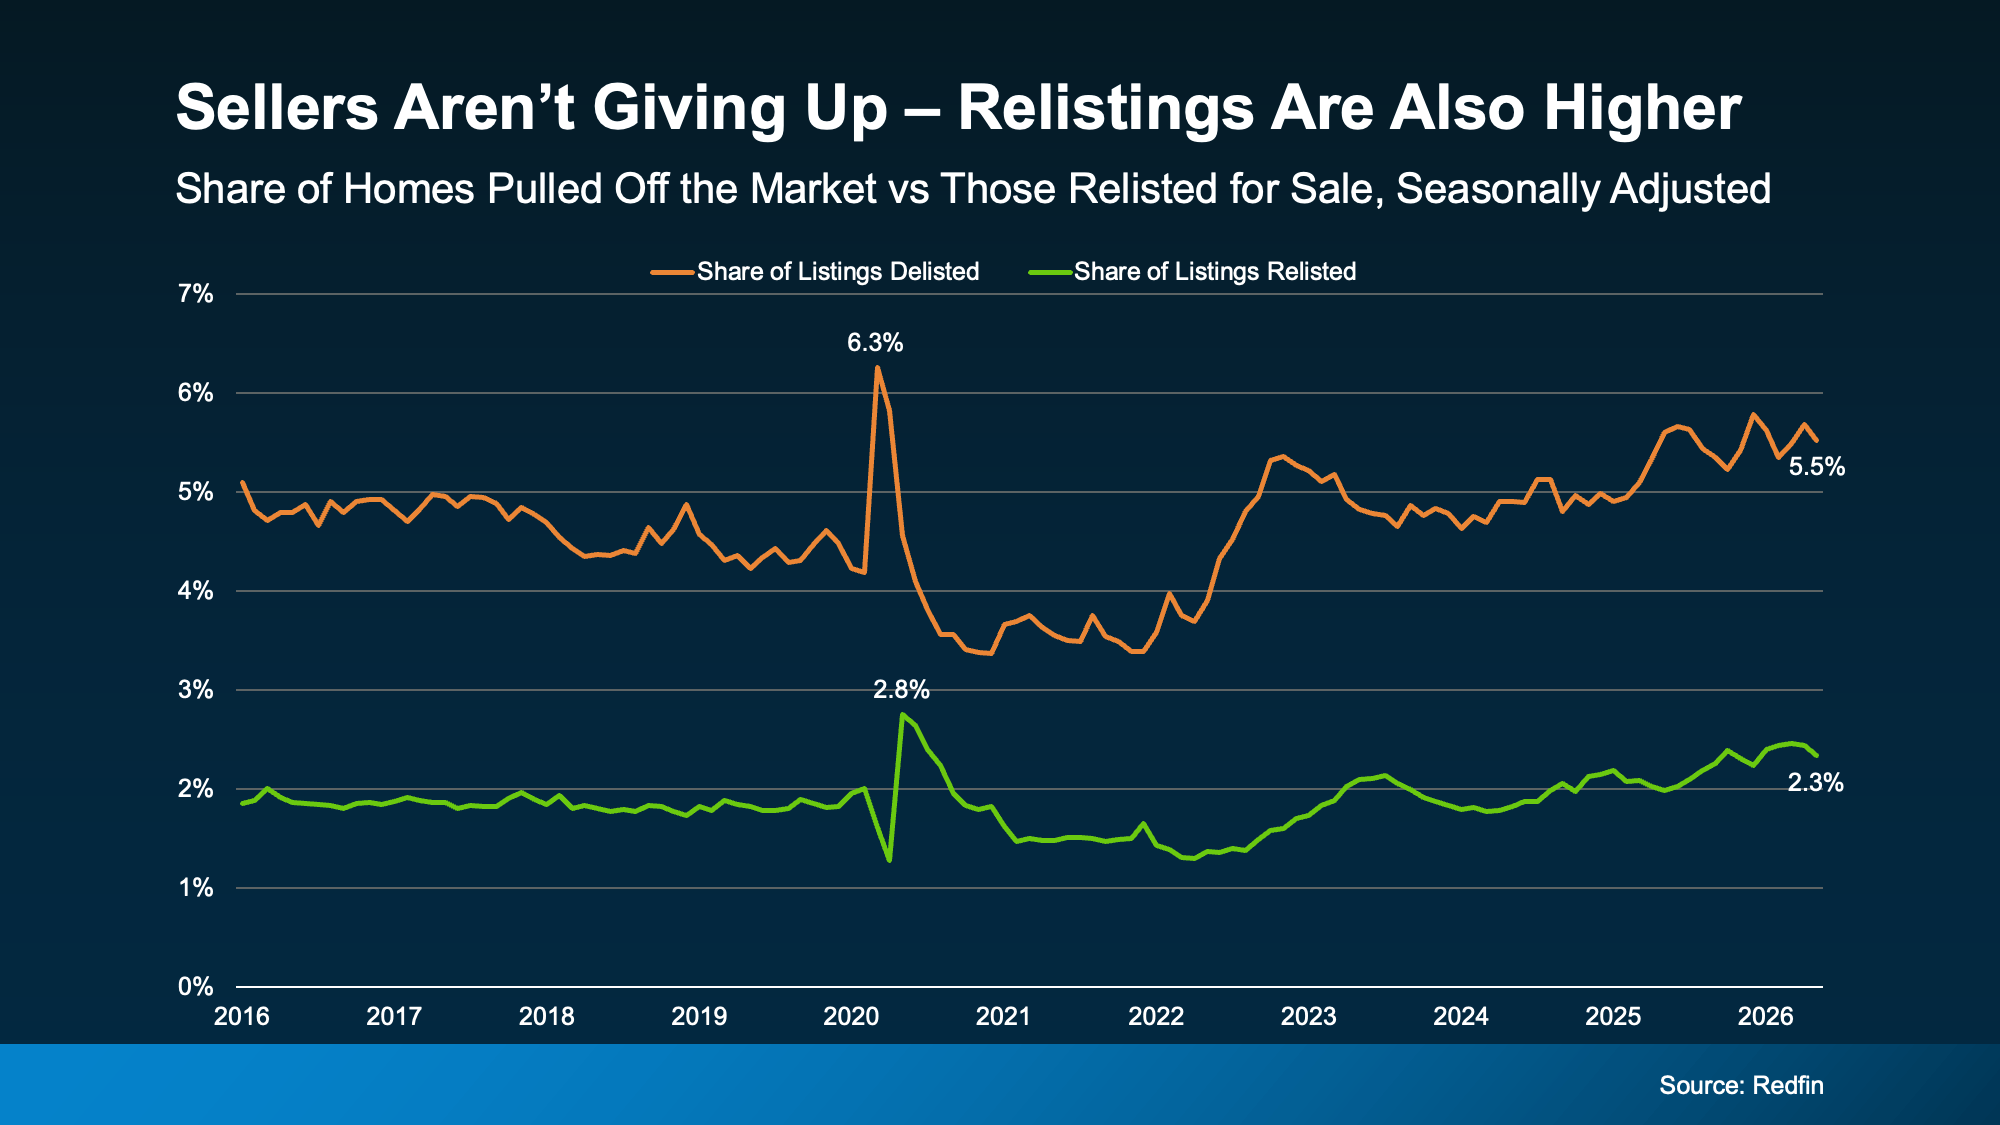
While 5.5% got pulled in May, 2.3% were also put back on the market (see graph below):

a graph of sales and prices

That’s a signal sellers aren’t giving up or running away in large numbers.

Some are simply stepping away briefly before deciding to try again. That tells you this often isn’t a permanent decision. In many cases, it’s a pause – and the seller comes back with a different approach.

A lot of the time that change in the overall strategy is all that’s needed to finally get a house sold. 

And just in case you need more proof this isn’t a reason to worry, check this out. Buyer activity may be starting to pick back up – and that could bring more sellers back in or, at least, prevent some sellers from pulling back. 

The National Association of Realtors (NAR) reports existing home sales increased 3.2% in May. That’s the biggest increase since December. As the Wall Street Journal puts it: 

“Home sales in May posted the biggest rise this year, a sign that the housing market’s crucial spring selling season may be showing signs of life after a sluggish start.”

That doesn’t sound like a market in trouble.

Bottom Line

If you’re seeing headlines about how a record number of sellers are taking their homes off the market, don’t panic. It’s not a warning of an impending crash. It’s a market adjusting.

House Been Sitting on Mt. Hood? Could Be a Deal!

by Liz Warren

That House That’s Been Sitting Could Be Your Best Shot at a Deal


Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.

Where Some Buyers Are Finding Better Deals

If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.

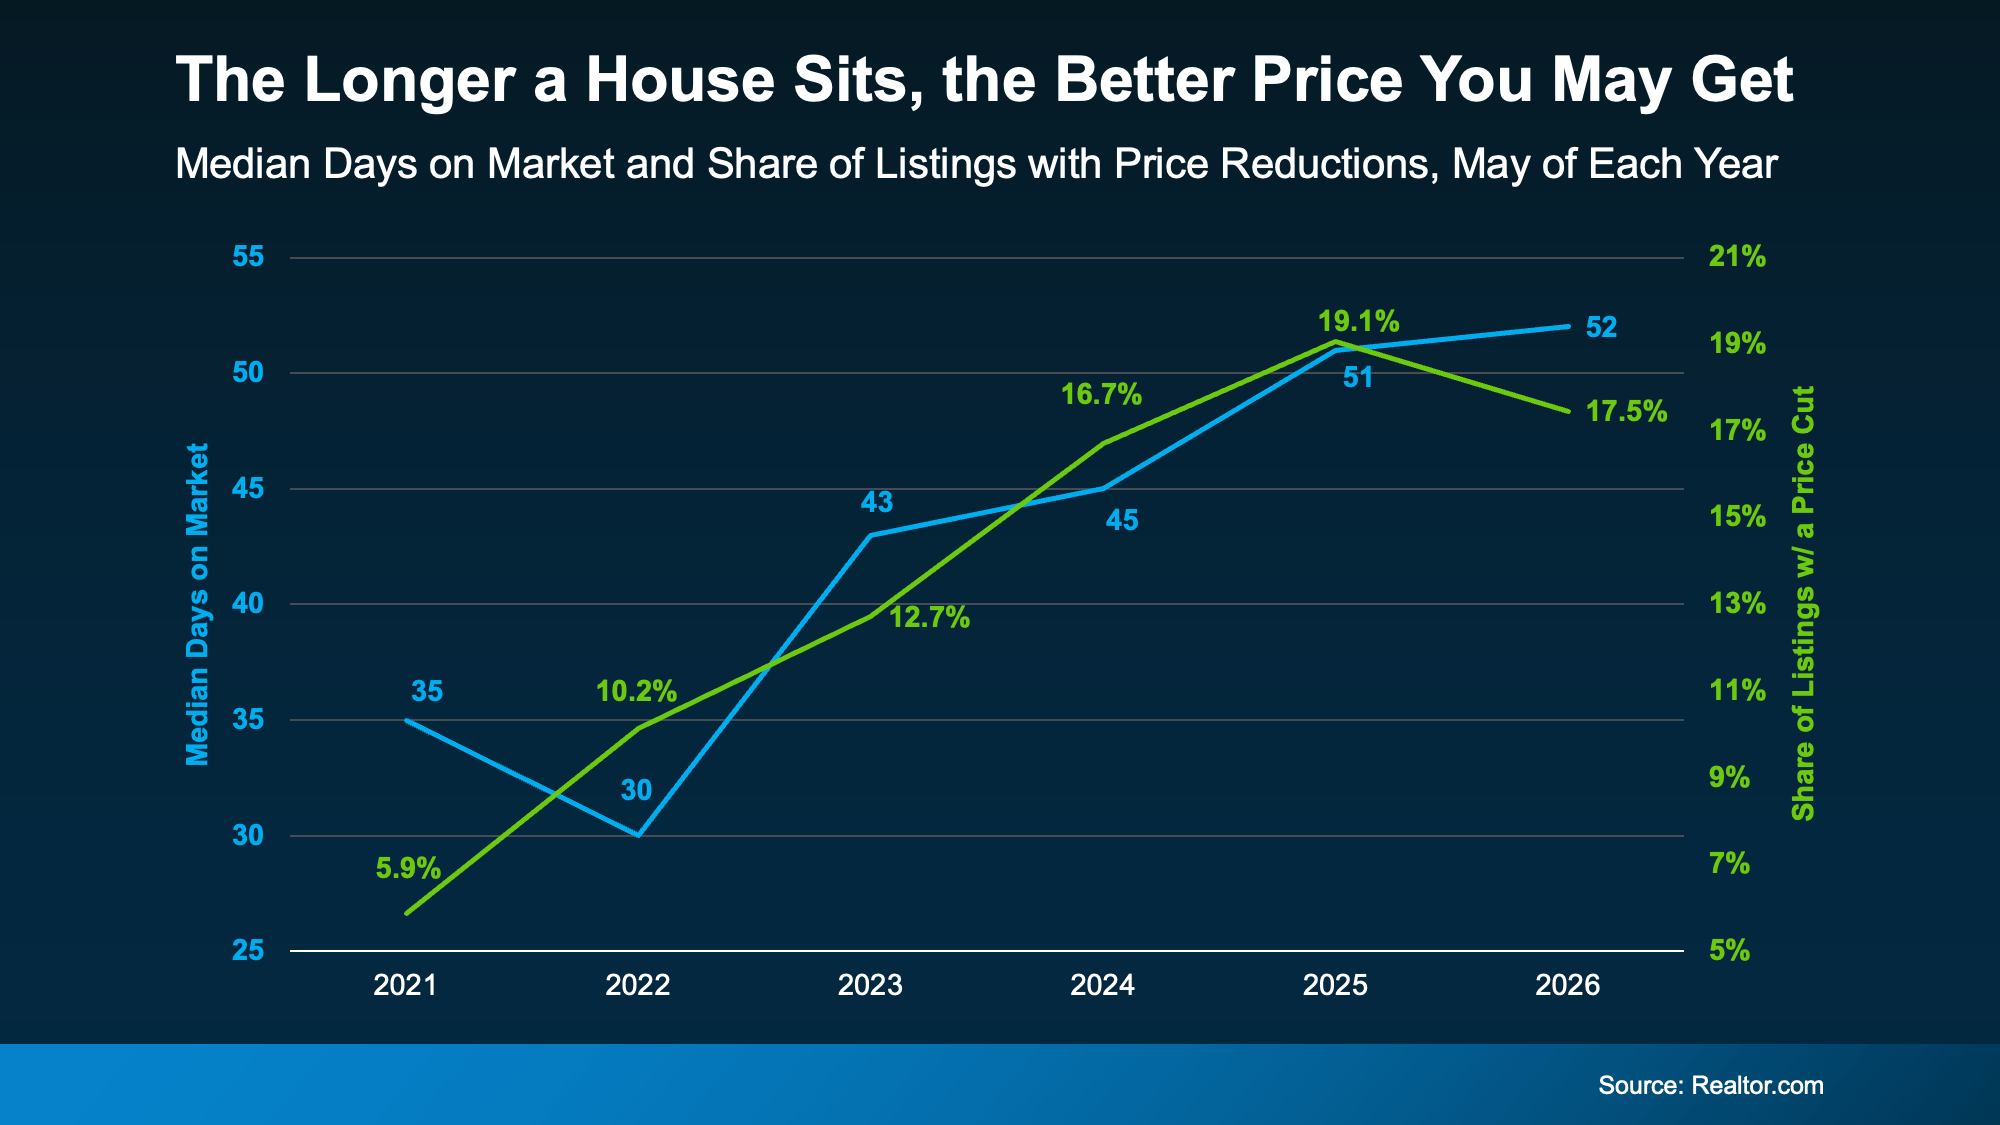
Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):

a graph with numbers and lines

The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.  

And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.

Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.

Lingering Doesn’t Always Mean Something’s Wrong 

Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.

According to Redfin, common causes are:

  • The asking price was set too high to start

  • The home didn’t show well online

  • There are a lot of homes for sale in the area, so it just got buried

So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.

How To Turn a Lingering Listing into a Win

So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.

The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.

The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.

A local agent has the context to tell which homes are the real opportunities and which are skippable.

Bottom Line

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, let’s connect.

Is It Still a Seller's Market on Mt. Hood?

by Liz Warren

Is It Still a Seller's Market? Here's What the Data Says.


Mt. Hood Home for Sale on Sleepy Hollow Drive


Remember a few years back when sellers held all the power and buyers were stuck offering way over asking or waiving inspections just to get a chance at the house? In many markets, those days are behind us.

While it’s going to vary by area, more metros are slowly shifting to favor buyers, and the market is starting to look a lot more like a two-way street again.

And that balance is something we haven’t had in a while.

Whether you're buying or selling, here's what you need to know about what's changing and what it means for your move.

The Most Buyer-Friendly Market in Years

The national data tells an interesting story right now. According to Realtor.com:

"The national housing market is balanced but gradually loosening as the cycle moves in a more buyer-friendly direction . . ."

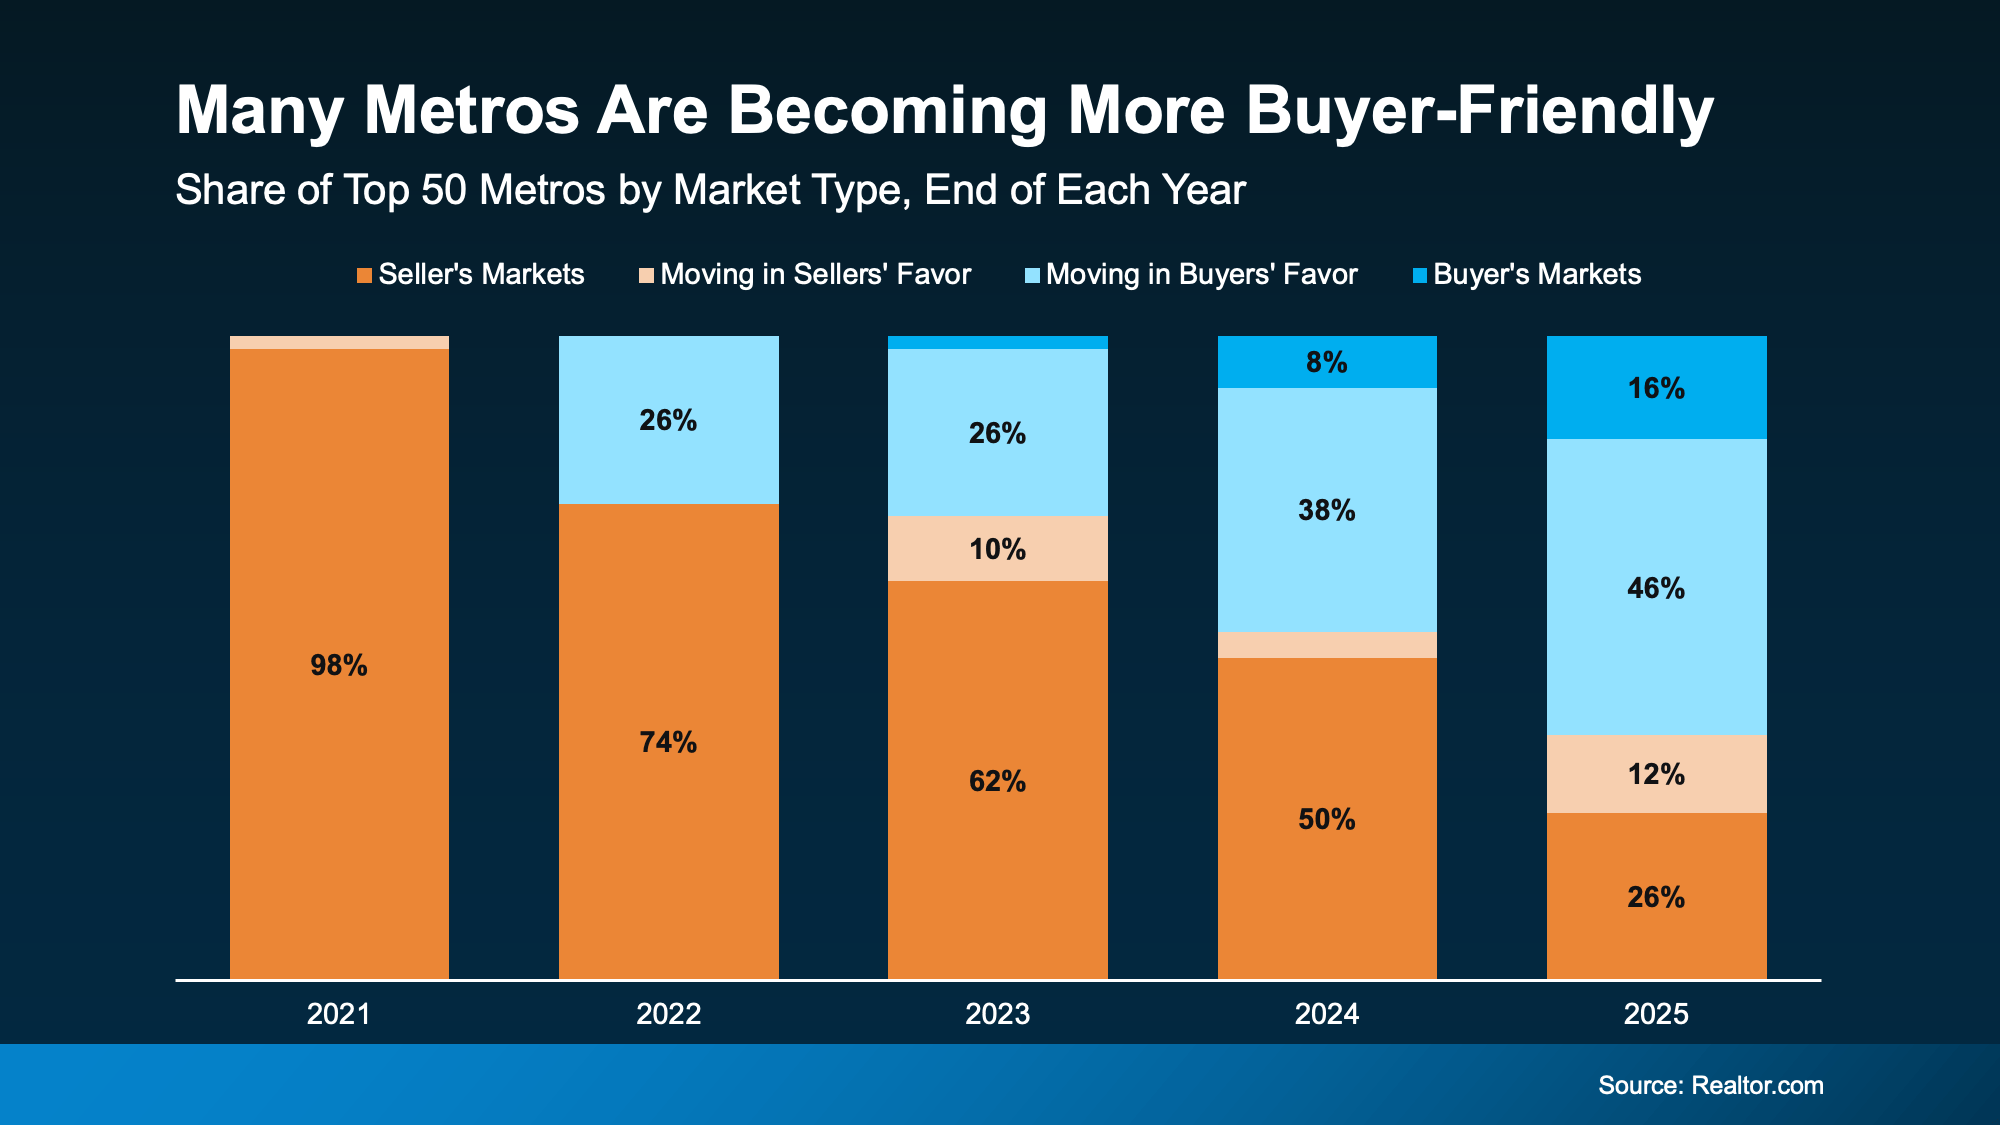
That’s because, over the past few years, more and more metros have been flipping back to more buyer-friendly terms as inventory’s grown. And when you zoom in on the latest Realtor.com data for the top 50 metro markets over time, the trend becomes really clear (see graph below).

Back in 2021, almost all major metros were seller's markets. By the end of 2025, only 1 in 3 still favored sellers. That's an obvious shift.

a graph of sales

And that changes how the market is going to feel for everyone. Sellers shouldn’t still expect 2021 conditions, but neither should buyers. At least, not generally speaking.

It’s Not the Same Story Everywhere

That said, who has the power ultimately depends on where you live. While more metros are leaning buyer-friendly lately, there are still plenty of strong seller's markets right now, too.

It really comes down to how much housing supply and demand there is in your area. And that varies enormously by region.

Sun Belt cities like Austin, Tampa, and San Antonio saw major building booms in recent years, giving buyers more options and more negotiating room. Meanwhile, cities in the Northeast and Midwest – think Rochester, Hartford, and Buffalo – didn't see that same wave, so inventory stayed tight and competition stayed fierce. As Jeff Ostrowski, Housing Analyst at Bankrate, explains:

“The formerly hot Sun Belt markets have cooled, while the Northeast and Midwest have stayed hot. The big driver here is construction activity. The softest markets now [have] experienced big booms that spurred new building, and that has led to a large supply of new and existing homes on the market in those places.”

Practical Advice for Your Move

To find out who has the power in your local market, talk to an agent. Because knowing what’s happening locally is going to be the key to setting the right strategy for your move.

If the market is working in your favor, great. Lean in and use it to your benefit. But if it’s not, all hope isn’t lost. Your agent can help you figure out how to approach any market.

Here's some practical advice if there’s a mismatch between your goal and local market conditions.

If you're buying in a seller's market:

  • Get pre-approved before you start shopping. It shows sellers you're serious.

  • Be ready to act fast when the right home hits the market.

  • Consider offering a quick closing date or flexible terms.

  • Work closely with your agent to craft a competitive offer.

If you're selling in a buyer's market:

  • Price it right from day one. Overpricing will cost you time and money.

  • Focus on curb appeal and staging to stand out in areas with more inventory.

  • Be open to offering incentives, like covering closing costs or a home warranty.

  • Expect buyers to negotiate and be ready to be flexible.

Bottom Line

Right now, local markets are moving in very different directions. And your strategy as a buyer or seller should reflect your market.

Want to know which way our local market is leaning and what that means for your move? Let's connect.

Timberline Gondola Project Just Cancelled.

by Liz Warren

The highly anticipated Timberline Gondola was officially cancelled today. The Forest Service project page confirms the cancelation. 

After a low snow winter and escalating insurance premiums, Timberline can't catch a break! The mountain will be closing for summer skiing around mid July cutting things short by weeks. Many ski camps didn't come this year for lack of snow pack. 

The local mountain economy is and will be suffering with all of this news. Please support our local businesses.


Record High Mortgage Debt Sounds Scary. Here’s What the Headlines Leave Out.


You may have seen the headlines lately about mortgage debt in America hitting a record high. And maybe your brother-in-law brought it up at the dinner table like he’s been waiting all week to spark a debate.

Here's the thing. He's not wrong. But he only has half the story. And the half he's missing? It changes everything.

Spoiler: homeowners are on stronger footing than the headlines suggest, and the housing market has more going for it than most people realize.

The Headline Number Is Real, But It’s Missing Context

Yes, according to the Federal Reserve, there is currently about $14 trillion in mortgage debt in the United States. That is an all-time high. And when you hear that alongside stories about people struggling to pay their bills, it's easy to assume the worst.

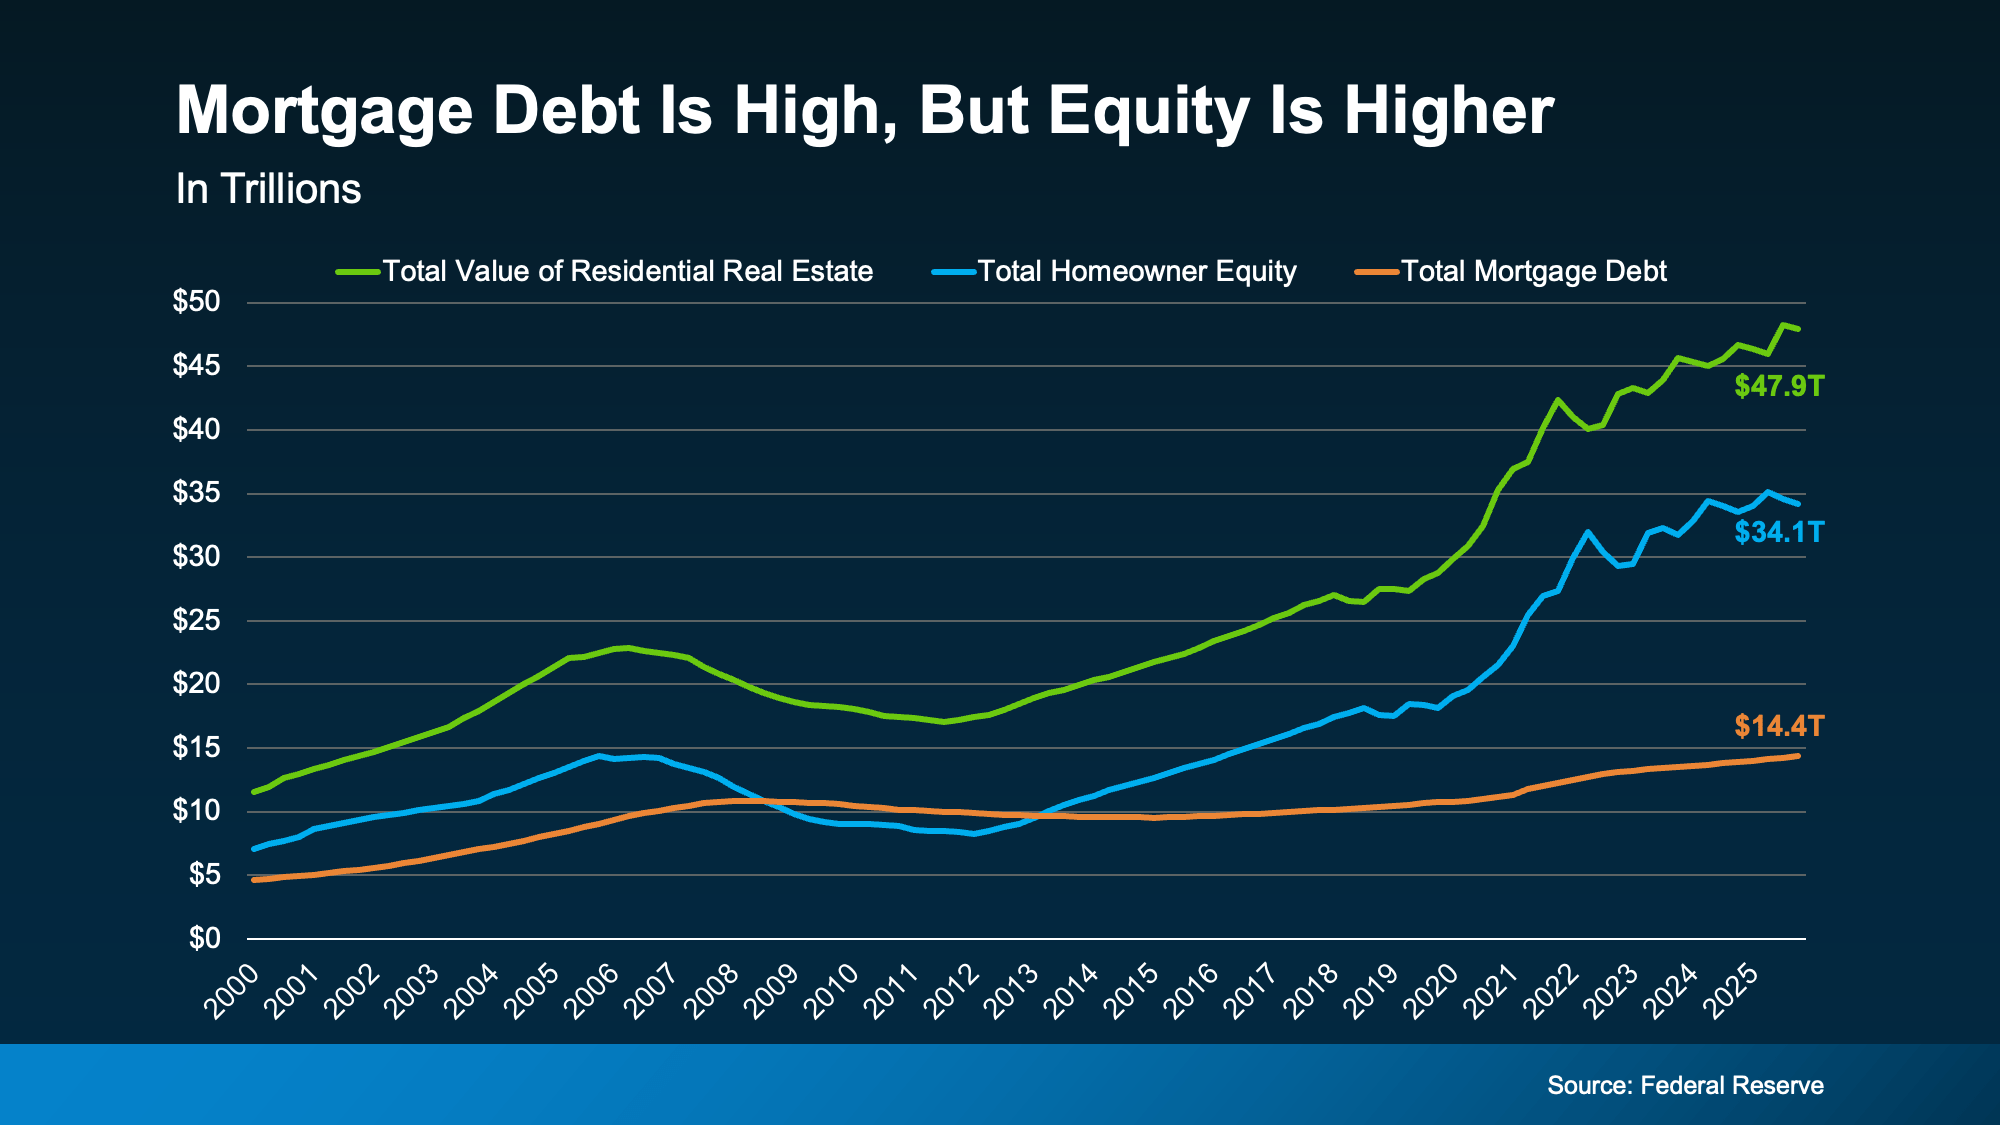
But here's what the data actually shows (see graph below):

a graph of a graph showing the value of a mortgageThis chart from the Federal Reserve tracks three things from 2000 to today: the total value of all U.S. homes (the green line), the equity homeowners hold in those homes (the blue line), and the total mortgage debt owed on them (the orange line).

Right now, home values sit at $47.9 trillion. Homeowner equity is at $34.1 trillion. And the mortgage debt everyone’s worried about? It’s $14.4 trillion.

Debt is at a record high, sure. But the equity homeowners have built up is more than double that number, and it’s also near a record high.

Here's the part worth pausing on. See the years between 2008 and 2013 where the orange line was higher than the blue one? That's when the housing market was in genuine trouble. When debt exceeds equity like it did back then, homeowners have no cushion.

So, when prices dropped in 2008, millions of people owed more than their homes were worth and had nowhere to go. That's what a housing crisis actually looks like. That's not what's happening today. Right now, it’s just the opposite.

The gap between what people owe and what they own has never been wider – in a good way. Today, they have far more equity than debt.

Most Homeowners Are in a Rock-Solid Position

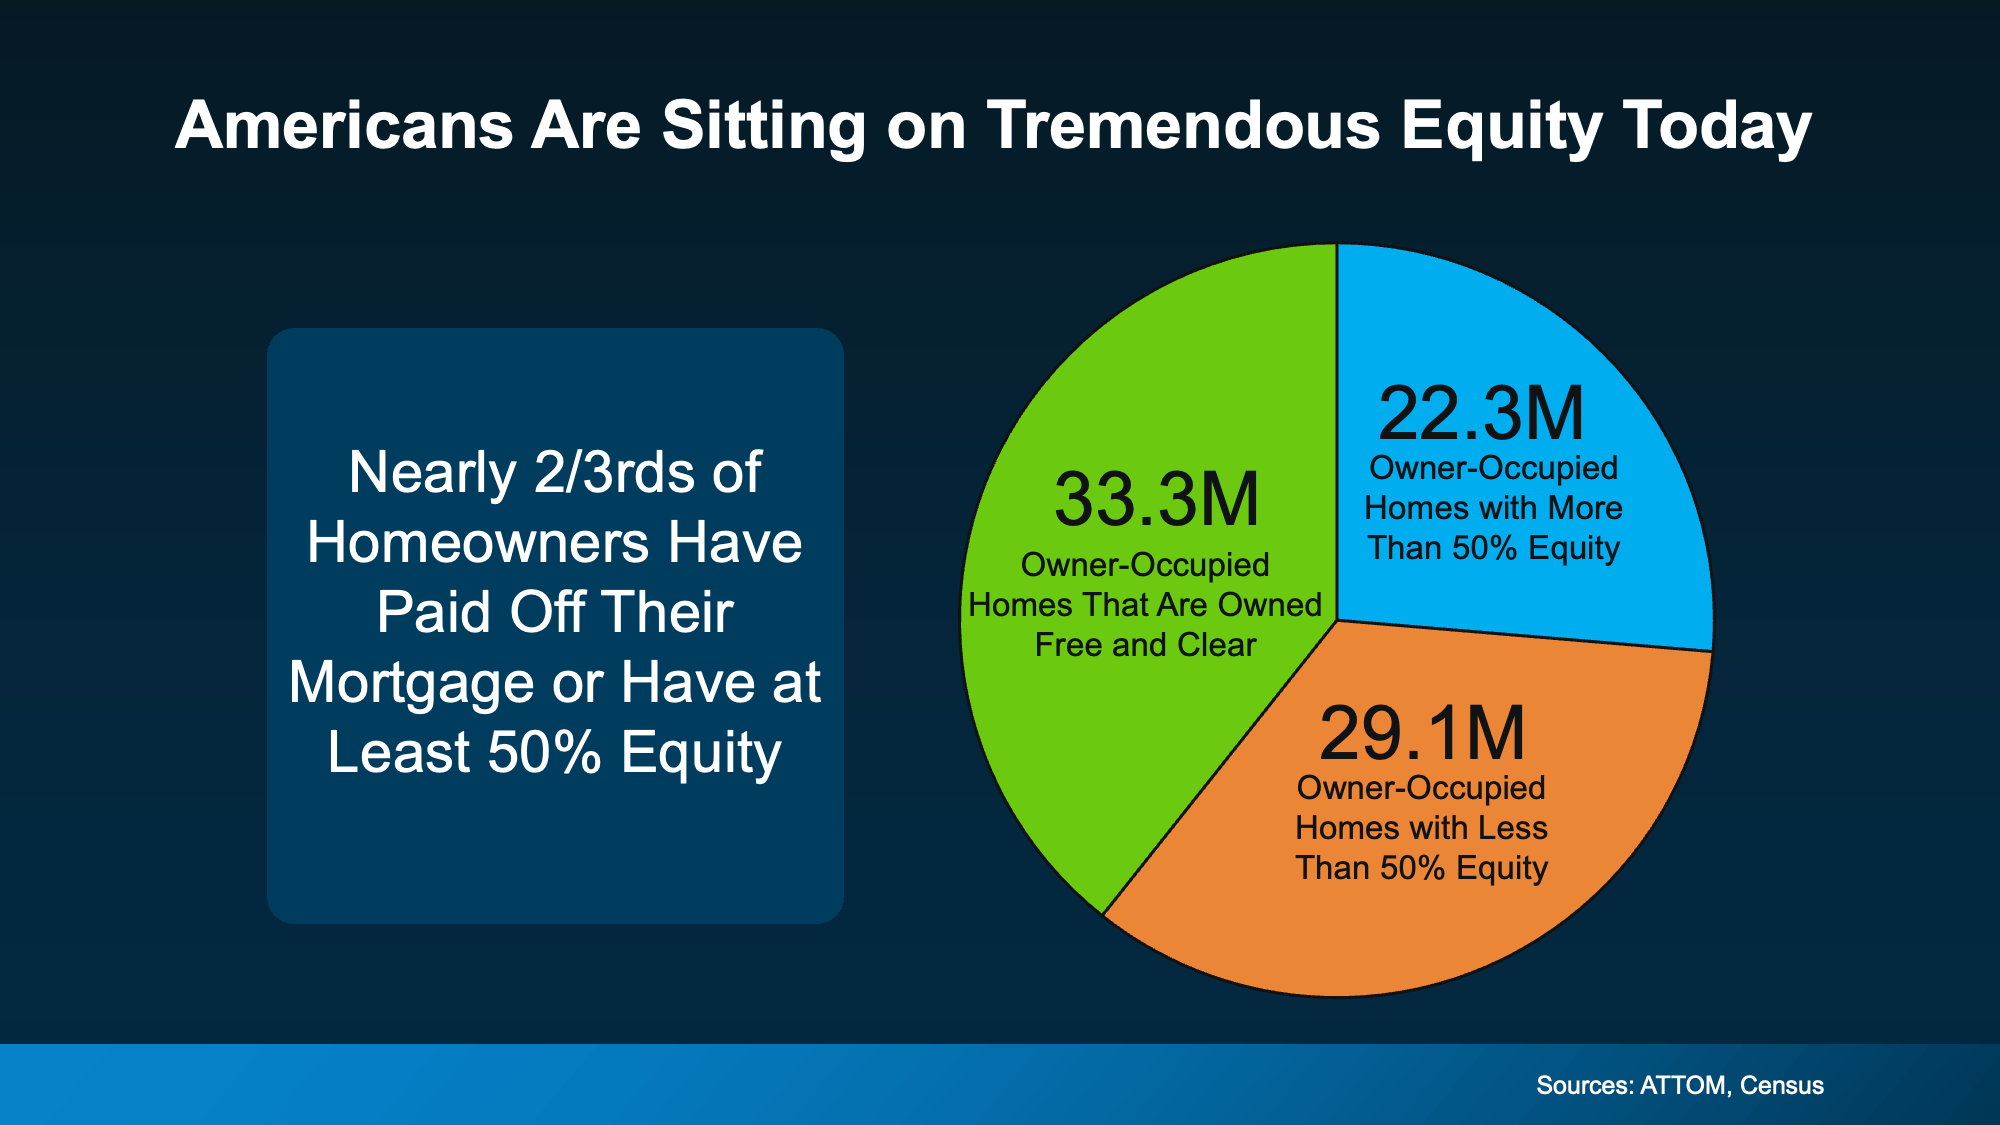
So, we know equity is high nationally. But what does that actually look like at the individual homeowner level? This next chart uses data from ATTOM and the Census to put it in perspective:

a pie chart with textOut of all owner-occupied homes in the country, 33.3 million are owned completely free and clear – no mortgage, no lender, no risk of foreclosure. Another 22.3 million homeowners have more than 50% equity in their homes.

Add those together, and you're looking at nearly two-thirds of all homeowners who have either paid off their mortgage entirely or have such a substantial equity stake that they're in an extremely stable position.

The remaining slice – 29.1 million homes with less than 50% equity – isn't a sign of distress, either. That includes plenty of people who recently bought, are building equity over time, and are doing just fine. 

The point is this isn't a market teetering on the edge. It's a market built on an unusually strong foundation.

Bottom Line

Record mortgage debt makes for a scary headline. But context matters.

Equity is near an all-time high, home values have surged, and the vast majority of homeowners are in a position of real financial strength. The conditions that made 2008 a crisis simply don't exist right now.

If you're wondering what all of this means for your situation, whether you're thinking about buying, selling, or just trying to make sense of the market, reach out anytime. No pressure, just answers.

More Sellers Are Open to Negotiating Right Now

by Liz Warren


Displaying blog entries 11-20 of 568

Syndication

Categories

Archives