Real Estate Information Archive

Blog

Displaying blog entries 1-10 of 470

A Mortgage Rate Buydown Could Make Your Next Home More Affordable


You want to find the right home, but you also need the right monthly payment. And that can be hard when it feels like just about everything right now is putting a squeeze on your budget. 

But there’s a tool that can help, and many buyers have never heard of it – it’s called a rate buydown. Here are the basics.

What Is a Rate Buydown?

When you’re borrowing money to buy a home, it usually works like this. The higher your mortgage rate, the bigger your monthly payment. And with rates where they are now, some buyers are feeling the crunch. That’s where a buydown can really come in handy.

A buydown lets you pay some money upfront to get a lower mortgage rate – and by extension a better monthly payment. Basically, it’s a way to get a lower mortgage payment without waiting for mortgage rates to fall. 

There are two main types, and they work a little differently. 

Temporary Buydowns: Starting Smaller

A temporary buydown lowers your rate for a specific amount of time – usually the first one to three years. When the buydown period is up, you begin making the full payment amount. The loan's official rate stays the same - you're just getting help with part of the payment in the early years.

Think of it like a gift card for your mortgage. Money goes into an escrow account at closing. Each month, part of your payment comes out of that account instead of your pocket.

Here are the most common options when it comes to temporary buydowns:

  • 1-0 buydown: Your rate is 1% lower for the first year.

  •  2-1 buydown: Your rate is 2% lower the first year and 1% lower the second year.

  • 3-2-1 buydown: Your rate is 3% lower the first year, 2% lower the second, and 1% lower the third.

Permanent Buydowns: Lower Forever

A permanent buydown is a bit different. The big draw here is that they last for the entire loan, which could be 15 or 30 years – not just a couple of years like a temporary buydown. But normally, the monthly savings are smaller.

Here’s how this one works.

It’s paid for with points. Generally, one point equals 1% of your loan amount. And each point usually lowers your rate about a quarter of a percentage, but this differs from lender to lender. The important distinction? 

  • A temporary buydown gives you short-term payment relief. 

  • A permanent buydown can lower your payment for as long as you keep that mortgage.

Why Buydowns Are Worth Asking About Right Now

With more homes available for sale, more sellers and builders are offering incentives to attract buyers. Some are even willing to pay for your buydown. 

And whether that’s advertised up front or something you ask for in negotiations, it can have a bigger impact on your bottom line than you’d think. 

Take a look at this example comparing a seller-funded 2-1 buydown with a permanent buydown on a median-priced home. In this scenario, the seller would pay for the upfront buydown costs. Remember, these are estimates - your numbers will vary:
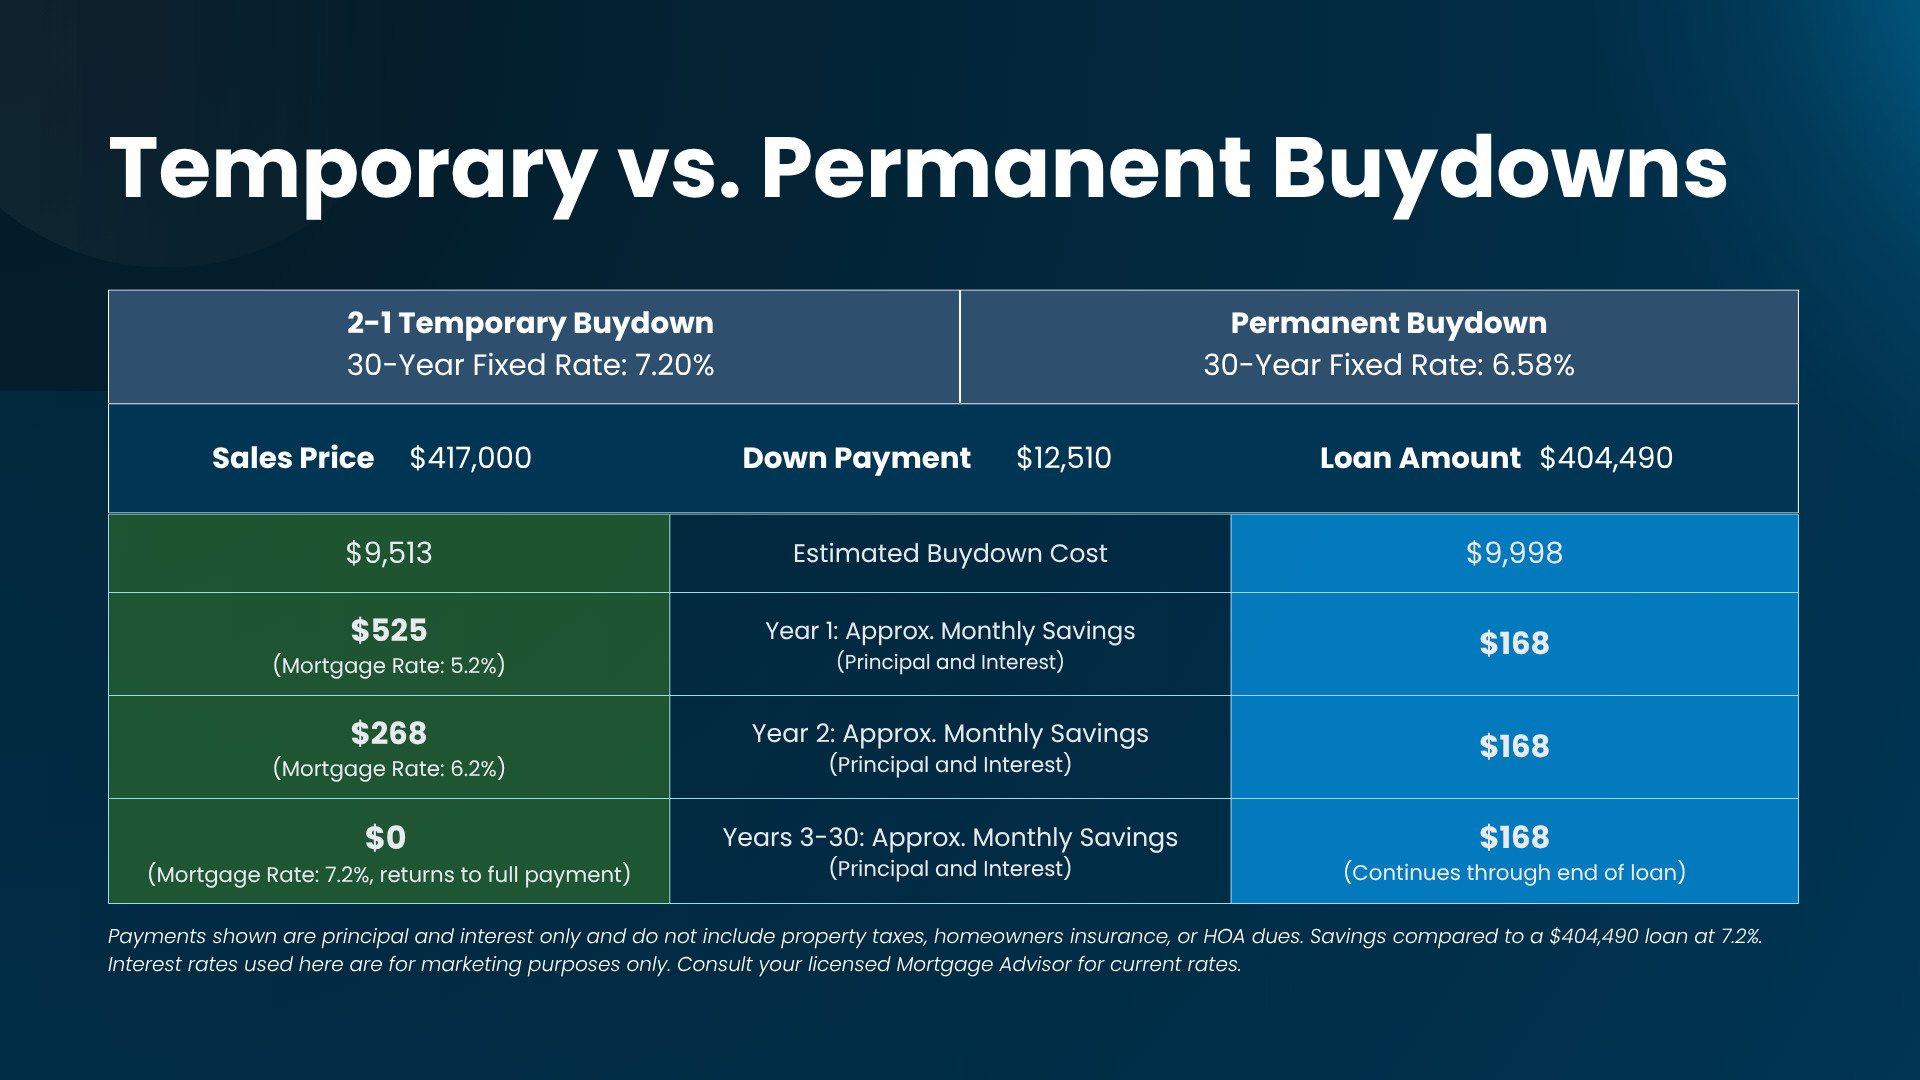
a blue and green chart with white text

In this example, the temporary buydown provides roughly $520 in monthly payment savings during the first year, compared with about $170 a month from a permanent buydown. 

That's a big difference in the short term. But there's an important tradeoff. 

As mentioned before, the temporary buydown savings don't last forever. Once the buydown period ends, the full mortgage payment kicks in. That's why it's important to compare the numbers over time, not just during the first year. 

How To Know if a Buydown Makes Sense for You

This is where a lender can really help you explore your options. A buydown isn't automatically the best choice for every buyer. It depends on your budget, how long you plan to stay in the home, and what you're trying to accomplish.

A temporary buydown could give you extra room in your budget during the first couple of years, when you're also managing moving expenses and settling into your new home. And if you expect your income to go up over time, this can be a good option.

On the flipside, a permanent buydown could make more sense if you plan to stay put for years and want the reassurance that the savings are sticking around until you move.

Either way, if you’re considering a buydown, the advice is simple. 

  • Make sure you can comfortably afford the full mortgage payment, even if you're starting with a temporary reduction. 

  • Factor in what it could look like if the payment goes up after the buydown period ends. You want to be sure your budget can handle it. 

  • Remember, lenders check whether you can afford the full payment, not just the discounted amount. 

Bottom Line

If you've found a home you love but the monthly payment is giving you pause, talk to your agent about buydowns. Then, meet with your lender to see the real numbers for your situation.

A buydown could give you another way to make the numbers work, especially if a seller or builder is willing to help. Who knows it may just be the difference between  "maybe someday" and "welcome home."
3 Things Mt. Hood Sellers Need to Know About Pricing

by Liz Warren

3 Things Sellers Need To Know About Pricing Today


If you're getting ready to sell your house, you've probably heard how important it is to price it right. And that's especially true right now. 

Today's buyers have more homes to choose from and they’re feeling pinched by today’s mortgage rates. That makes them more selective. And that means having the right pricing strategy matters more than ever. 

That starts with understanding these three things. Because, with the right approach, you can still put your house in a great position to sell.

1. Price for Your Competition, Not Just the Comps

It's natural to look at what your neighbor's house sold for and think yours should sell for something similar. And those comparable sales (or comps) absolutely matter. But they only tell part of the story. Here’s why.

Buyers aren't shopping against what sold three or even six months ago. They're comparing your house to what's available right now.

That's why your agent will look at more than just recent sales. They'll also consider the houses currently for sale, what's going under contract, and how your house stacks up against those options to find the right price for your house. 

The goal isn't necessarily to price lower than everyone else. It's to make sure buyers see the value in choosing your house over the competition.

As Jake Krimmel, Senior Economist at Realtor.com explains:

“Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Understanding how your house compares to what's available today can help you feel more confident in your asking price.

2. Buyers May Still Negotiate, Even When Your House Is Priced Right

Getting your asking price right puts you in a stronger position from the start. But when an offer comes in, remember that price is only one part of the equation. 

Today's buyers may still negotiate on things like money toward closing costs or repairs, even when a house is priced well – and that’s not necessarily a commentary on your price, it’s just the norm for negotiation in today’s market. 

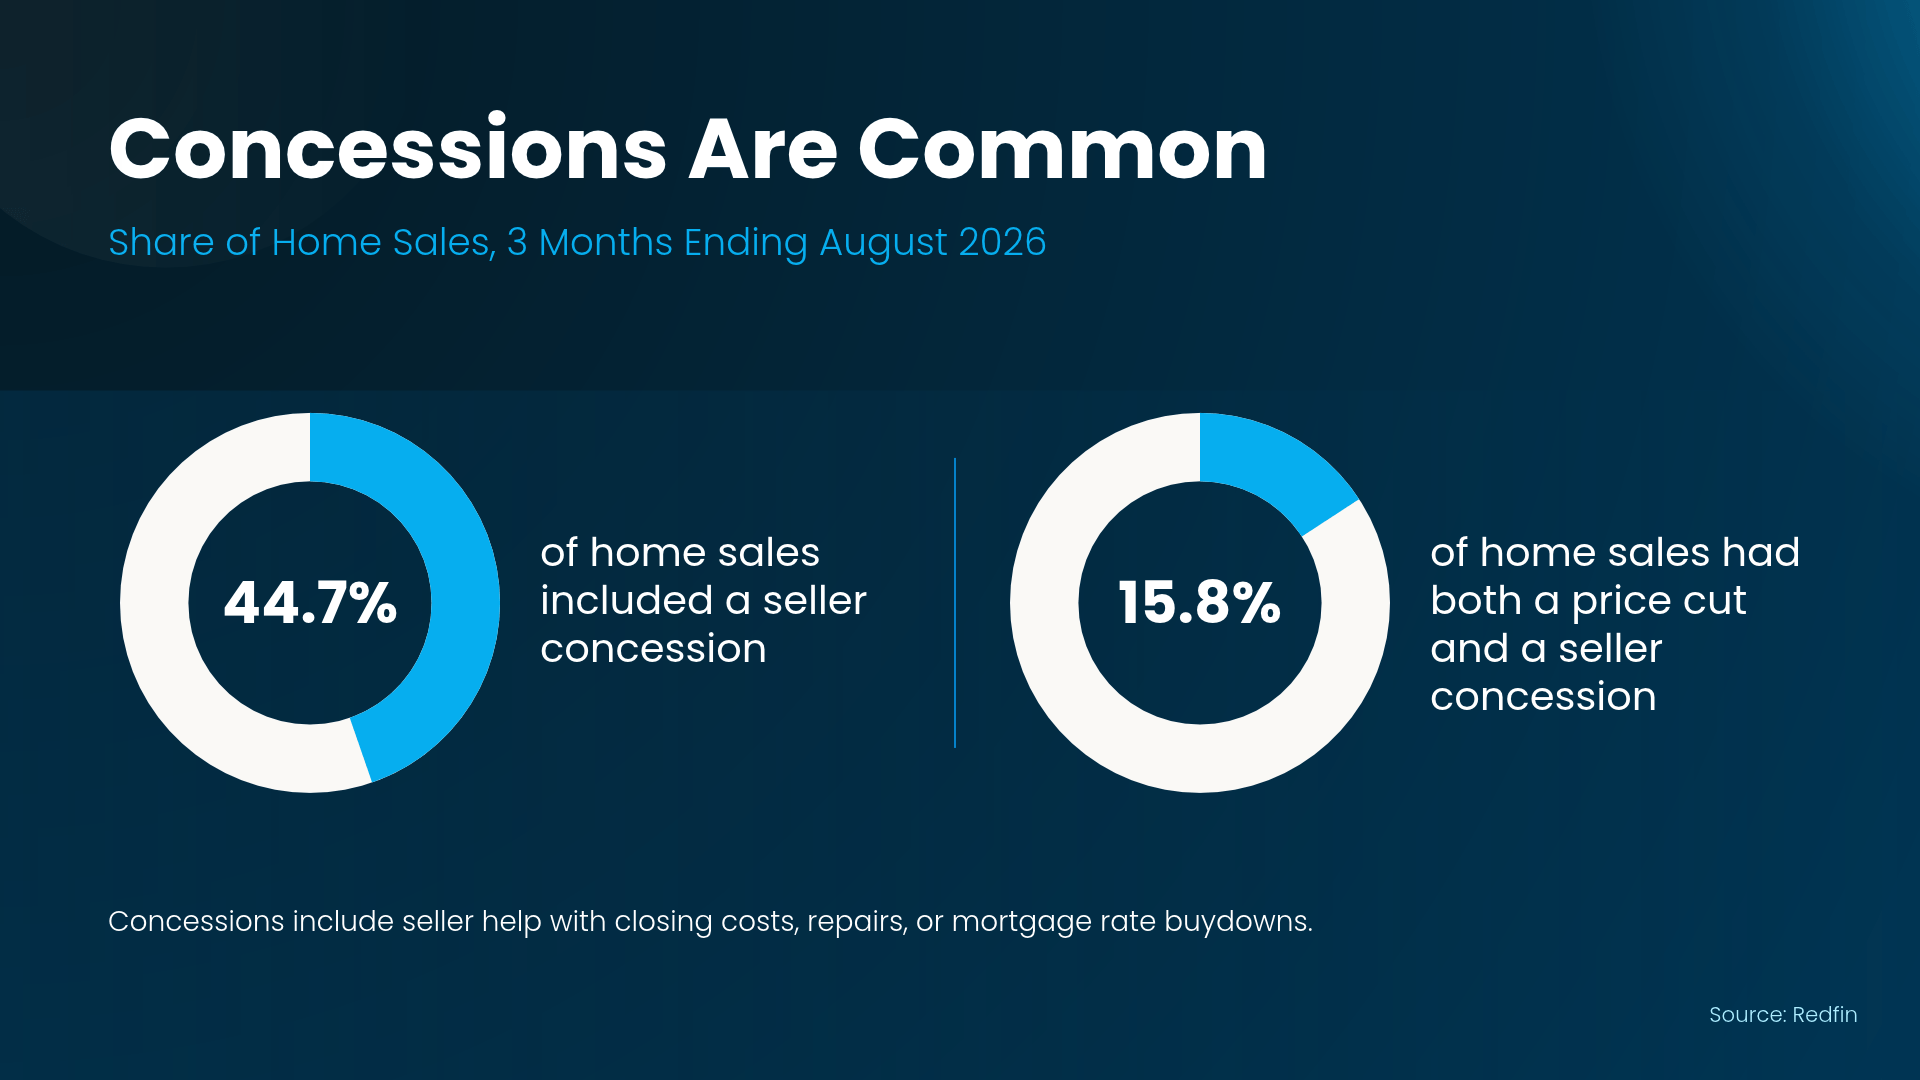
According to Redfin, 44.7% of home sales involve seller concessions. That’s just under half. And 15.8% had both a price reduction and a concession.

a blue and white pie chart

Now, that doesn't mean you have to agree to everything a buyer asks for. But sometimes offering a closing-cost credit or helping with a mortgage rate buydown could be what seals the deal. Other times, holding firm is the better move. Your agent will help you decide.

The best advice? Look at the whole offer, including what you'll actually walk away with, to decide what’s right for you.

3. Know When To Adjust Your Strategy

Even with a competitive price, some houses take longer to sell than others. And if yours isn't getting the attention or offers you expected, that doesn't mean your sale is off track. It just means it's time to take a closer look at what's happening.

Your agent can help you use buyer feedback and local market activity to figure out what adjustments, if any, could make a difference. 

  • Are buyers seeing your listing online but not scheduling showings? Maybe the photos or presentation aren't doing your house justice.

  • Are people touring but not making offers? It could be the condition, the price, or how your house compares to others they've seen.

  • And if buyers are making offers, but the terms aren't working for you, that may call for a different negotiation strategy altogether.

While you may worry that means you have to drop your price, that’s not always true. A price cut can help, but only if it addresses what's keeping buyers from making a move. 

That's why feedback, local competition, and an agent who knows how to interpret both are so important.

Bottom Line

Selling successfully today isn't about finding one magic number and hoping everything falls into place. It's about starting with a competitive price, understanding what buyers expect, and being willing to adjust your strategy when needed.

Want to know what it'll take to sell your house in today's market? Let's look at the competition, talk through your options, and build a pricing strategy that works for you.

How To Win Back Your Buying Power

by Liz Warren


What the Silver Tsunami Means if You’re Planning To Sell

by Liz Warren

What the Silver Tsunami Means if You’re Planning To Sell


If you’re following the housing market, you may have heard the term “silver tsunami” lately. It's the idea that millions of homes owned by older Americans could come onto the market as more homeowners reach retirement age and make their next move.

And when you hear a phrase like that, it's easy to picture a flood of houses hitting the market all at once. But that picture doesn't match the data.

This isn't expected to happen overnight. 

And if you're planning to sell, it's not a reason to put your plans on hold. Let's look at what the research actually says.

The Silver Tsunami Will Be More of a Gradual Shift

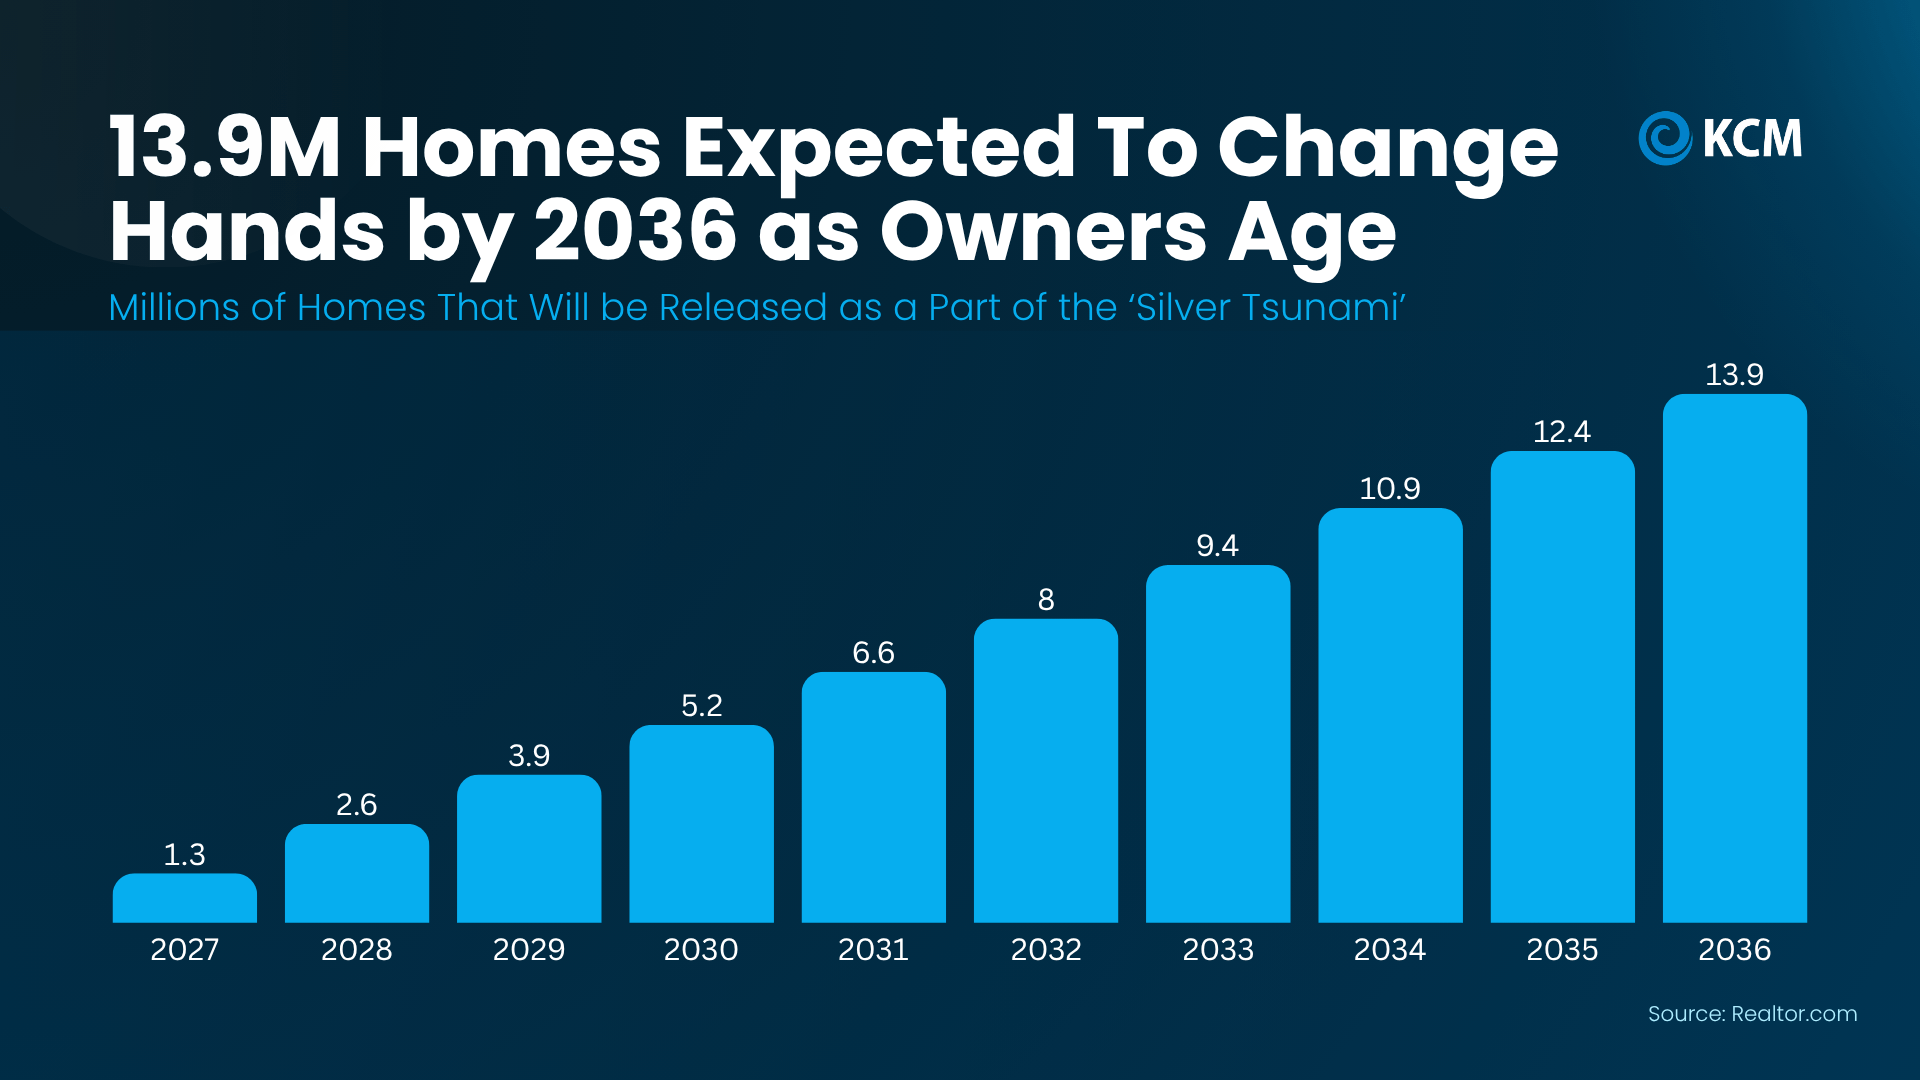
According to Realtor.com, about 13.9 million homes owned by older Americans are expected to change hands by 2036. Sure, that's a big number. But these homes aren't all expected to come onto the market at once.

The projections show this happening gradually over the next decade, with roughly 1.3 to 1.5 million homes changing hands each year (see graph below):

a blue graph with white text

Rather than a sudden wave of houses flooding the market, this is a gradual shift as longtime homeowners make decisions about where and how they want to live.

The term silver tsunami makes for a dramatic headline, but the actual data tells a much less dramatic story. And there’s another reason these homes won’t overwhelm the market.

The Market Has Room for More Homes

After the 2008 housing crash, builders significantly slowed construction. And for years afterward, they didn't build enough homes to keep up with demand. That led to a housing shortage we're still dealing with today.

And just how big a gap are we talking about? Estimates vary, but many experts say the U.S. is still millions of homes short. For example, a recent report from the White House Council of Economic Advisers explains:

“If homebuilding and the growth of the single-family housing stock had continued at their historical pace instead of falling dramatically after 2008, there would be 10 million or more additional single-family homes today.”

As more longtime homeowners sell, those homes will help a gap that’s already there. But they won’t push us over the edge. That’s because, at the same time, more households are expected to form in the decade ahead, and they’ll need homes, too. 

So, more homes becoming available over time isn't automatically a bad thing. It can give buyers more options and help create a more balanced housing market moving forward.

What Actually Matters When You Sell

Here's the takeaway if you're thinking about selling your house. The silver tsunami isn't something you need to plan your move around. What's happening in your local market is far more important than a national projection about the next decade.

That's because real estate is local. Some markets have more homes for sale than others. Some are seeing houses sell relatively quickly, while others are taking longer.

And those are the conditions that matter when you're deciding how to price, prepare, and market your house.

For example, an agent who knows your area can help you understand:

  • How many homes are for sale nearby. This tells you how much choice buyers have and how your house will compare.

  • What similar houses are actually selling for. That's one of the most important factors in setting a competitive asking price.

  • What buyers are looking for right now. Knowing which features and improvements matter most can help your house make a strong first impression.

And that's something you can act on today, regardless of what happens with the silver tsunami over the next decade.

The right strategy starts with understanding your local market and making decisions based on what's happening there, not what a dramatic national headline suggests might happen years from now.

Bottom Line

The silver tsunami may sound like a major wave of homes coming onto the market, but the research points to a gradual shift over the next decade, not a sudden flood of listings.

If you're thinking about selling, don't let that headline make you second-guess your plans. Let's talk about what's happening in our local market.

Will Rates Level Off in 2027?

by Liz Warren

Cash Is King on Mt. Hood

by Liz Warren

Who’s Buying Homes with Cash Right Now?


Ryan Serhant, CEO of SERHANT, says there isn’t just 1 housing market right now. There are really 4: cash buyers, buyers who need a mortgage, homeowners with low mortgage rates, and builders.

Today, let’s zoom in on the 1st group – cash buyers.

According to the National Association of Realtors (NAR), 27% of homes sold in September were bought with all cash. That’s more than 1 in 4 buyers. And that’s a pretty big number, especially when so many people are struggling with affordability.

So where is all that cash coming from? When you hear a number like that, it's easy to picture wealthy investors buying up houses left and right. But that’s not necessarily the case. Some of those cash buyers are actually homeowners who've built up enough equity to buy their next home outright.

Here's what you should know about who's paying cash and what that really means for the market.

Who’s Paying Cash?

Cash buyers tend to fall into a few groups, according to NAR:

  • Homeowners who sold a house and are using that money to buy their next one

  • People buying a 2nd home

  • Investors

So, it’s not all those big investors social media talks about. That 1st group may include people a lot more like you. Here’s how. According to Cotality, the average homeowner with a mortgage has about $310,000 in equity.

That’s a big deal right now. Many homeowners feel stuck because they don’t want to give up the low mortgage rate they have today. But once they learn they may have enough equity to move and pay cash for their next home, today’s rates don’t matter nearly as much. Because buying in all cash means…

  • No monthly mortgage payment

  • No need to borrow at today’s mortgage rates

  • No loan approval process, so you may be able to close faster

And even if the equity won’t cover the whole purchase, putting more of it toward the next home means borrowing less. That can mean a smaller monthly payment, too.

But cash buyers like this are more common in some places than others. And how big of a segment of your local market this is, is going to depend on where you live.

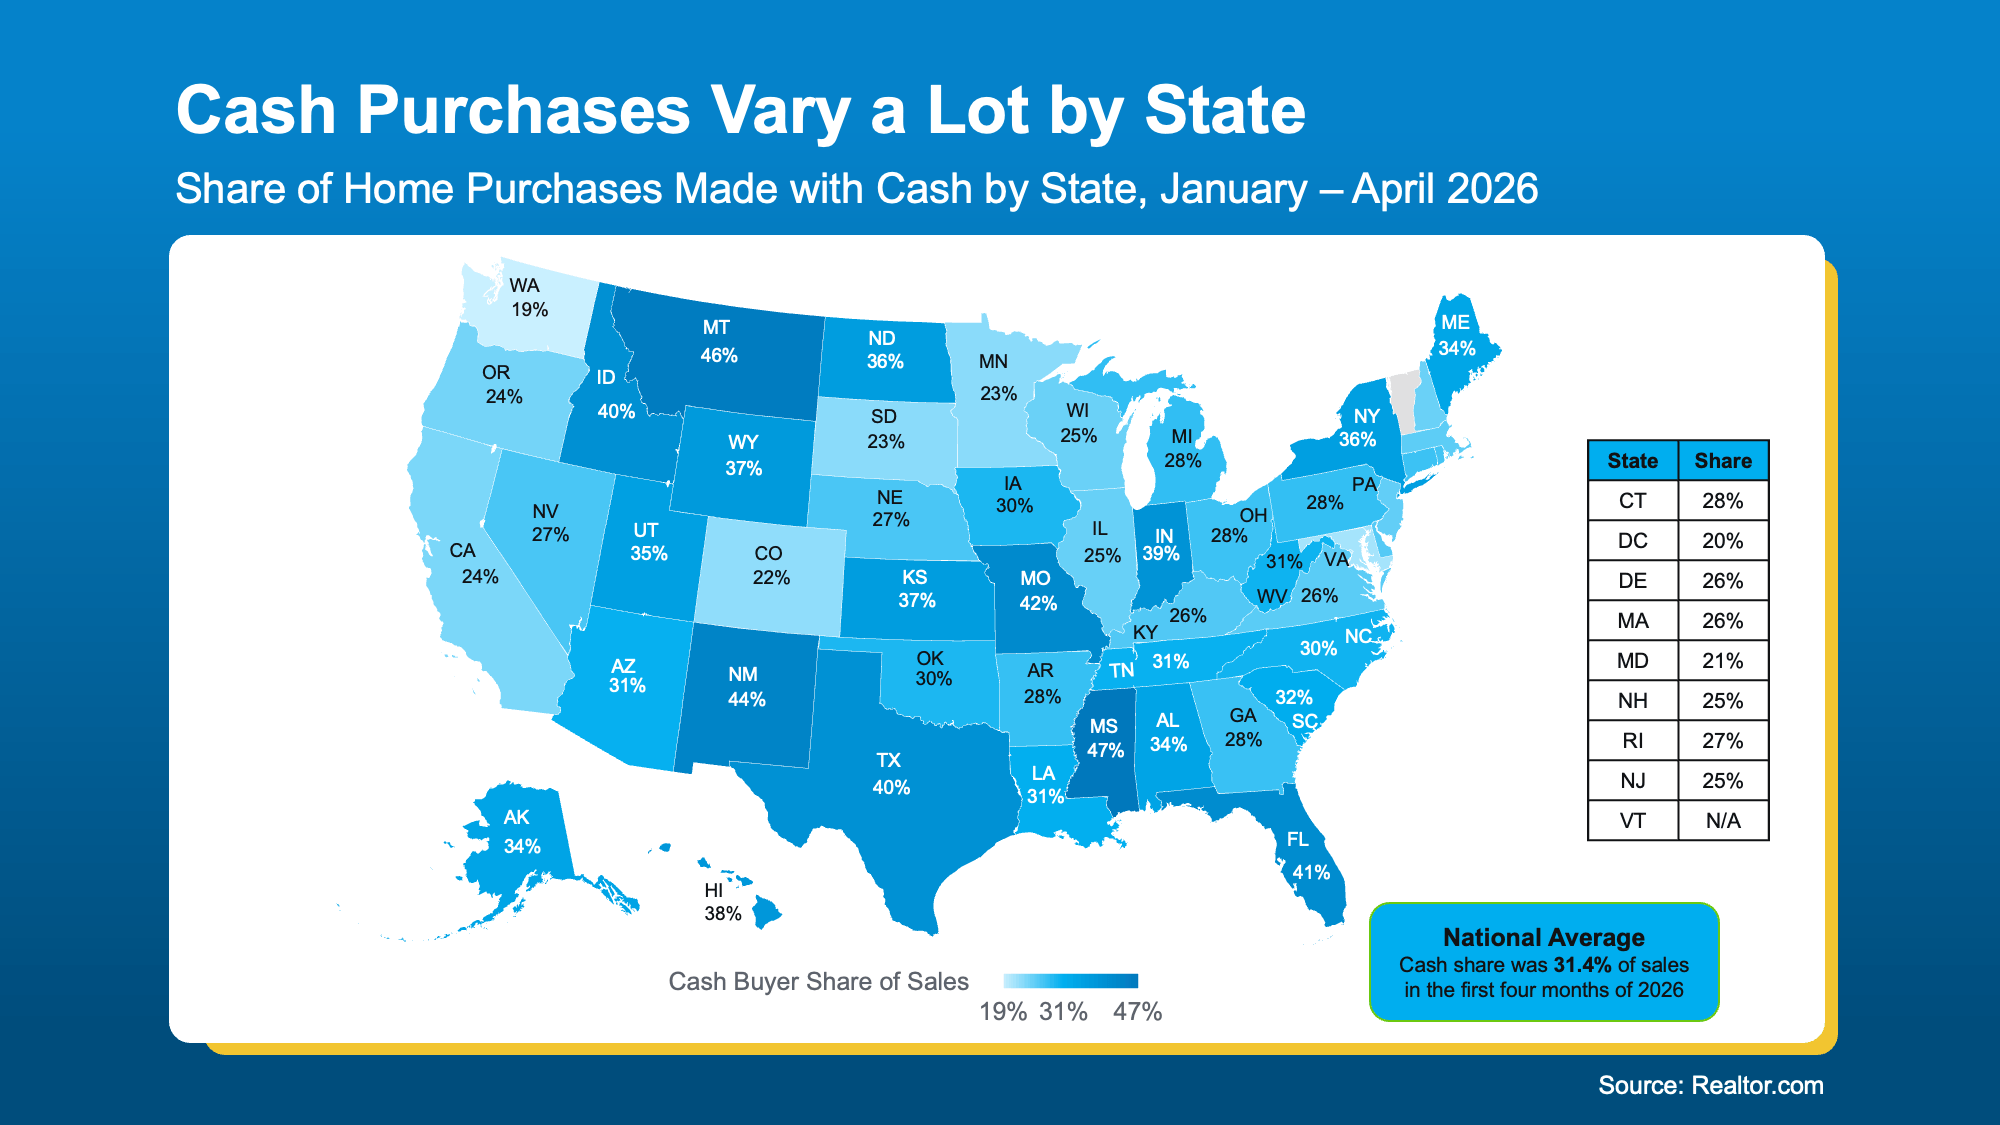
For example, Realtor.com data shows cash buyers made up almost 47% of sales in Mississippi and 46% in Montana earlier this year (see map below).

Where does your state fall?

a map of the united states

According to Realtor.com, the states with the most cash buyers reflect “a mix of affordability, wealth and buyer demographics.” Think places with lower home prices, or lots of retirees and 2nd-home buyers.

So, depending on where you live, you may see a lot more (or a lot fewer) cash buyers than the national number suggests. An agent who knows your area can tell you who’s actually buying near you.

Most Buyers Are Still Using a Mortgage

And if all of this has you thinking everyone’s paying cash, they’re not. If you’re planning to buy and need a mortgage, you’re actually in the majority.

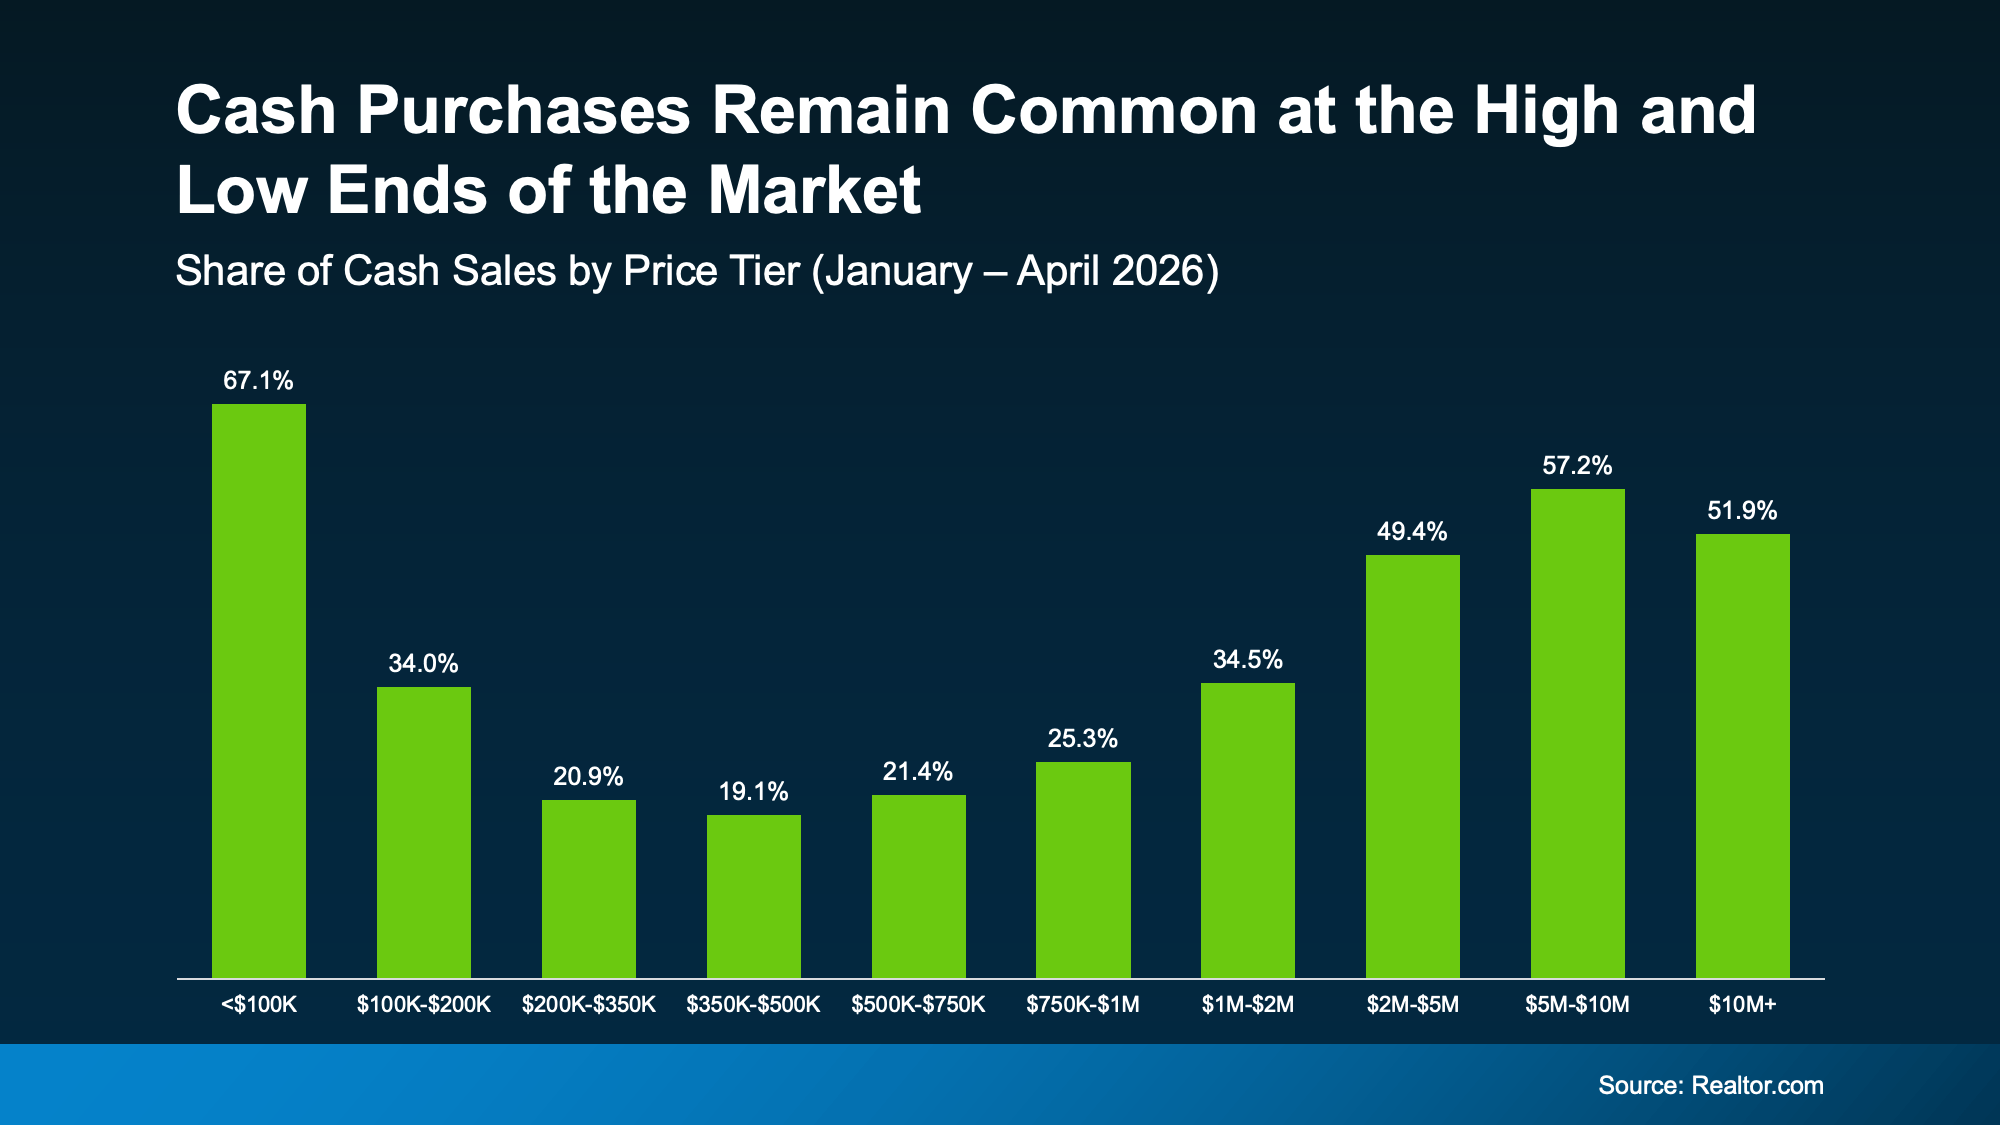
Based on NAR’s numbers, nearly 3 out of 4 home purchases still involve financing. And for homes priced between $200,000 and $750,000, only about 1 in 5 sold for cash, according to Realtor.com (see graph below):

a graph of green bars

That means most people buying in that price range are financing their purchase, too. So, there’s no need to assume you’re at a disadvantage just because you’re using a loan.

Cash Buyers and Your Move

So, what does all this mean for you? Maybe more than you think.

If you already own a house, you may have enough equity to make your next move more affordable than you realize. And if you're buying with a mortgage, remember, you're in good company. Most buyers are financing their purchases, too.

The takeaway? Don't make assumptions about what's possible based on how other people are buying homes. What really matters is your equity, your budget, and what’s happening in your local market.

Bottom Line

Cash buyers are a meaningful part of today’s market, but they aren’t the whole market.

Whether you’re hoping to put your equity to work or you’re buying with a mortgage, let’s look at how much equity you have and who’s buying in your area, so you know what your next move could look like.

Credit Scoring Is Changing: 3 Things Homebuyers Should Know


Quick, what credit score do you need to buy a home? If a number pops into your head, there's a pretty good chance it's wrong. And the right answer is getting harder to pin down, because the way credit scores are determined and delivered is changing - for the better.

Here's what you need to know in today's changing credit climate.

#1  Most People Are Guessing 

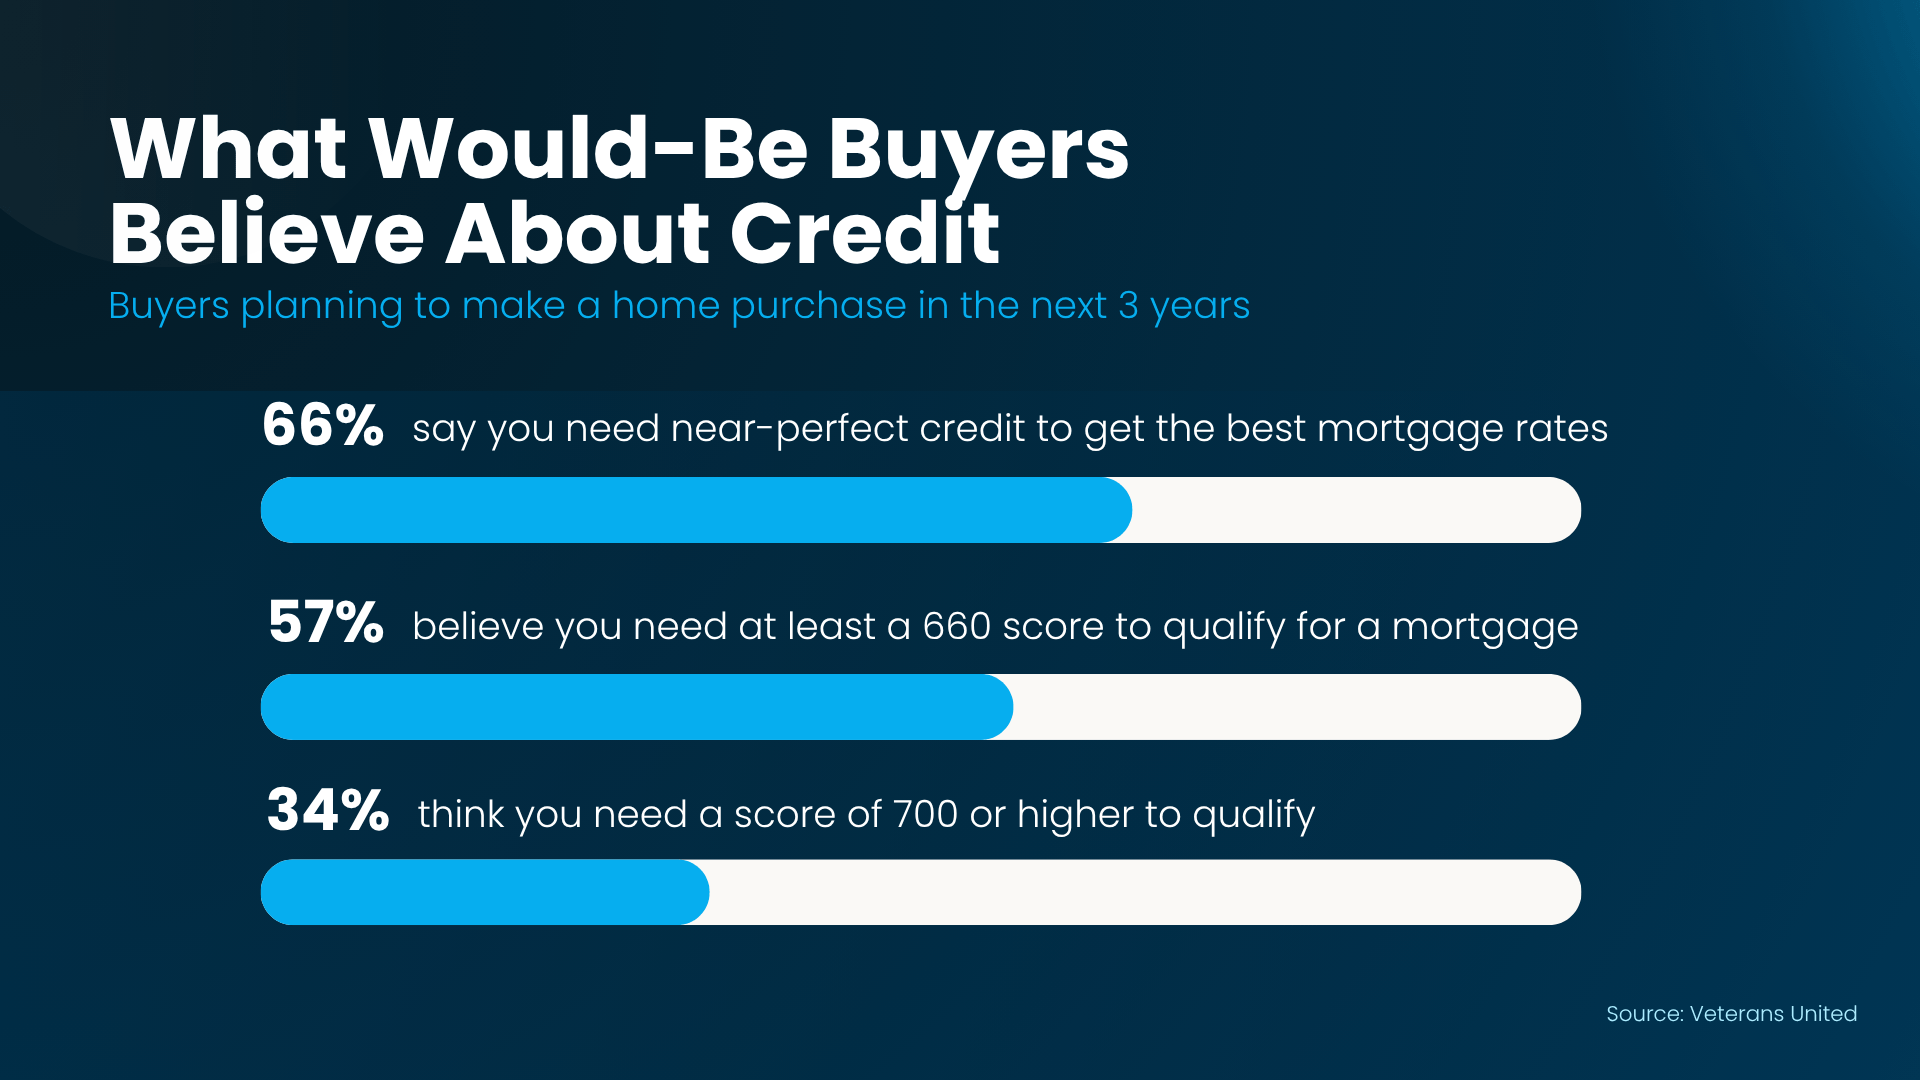
Fannie Mae has been tracking consumer perceptions about mortgage requirements since 2015 and found that consumers consistently overestimated the minimum credit score lenders required to qualify for a mortgage. As recently as 2023, the average guess was 652.

In reality, the long-standing benchmark for loans backed by Fannie Mae and Freddie Mac is lower, at 620, and today even that isn't a hard rule for every mortgage they back. 

Like the Fannie Mae research, a recent survey from Veterans United found consumers continue to overestimate what it takes to qualify for a home loan:

a blue and white survey

The takeaway? Guessing wrong can cost you. 

A renter who assumes their score is too low and they can't qualify for a mortgage may never take steps to find out for sure.

#2  Credit Rules Are Changing

For decades, the mortgage industry relied on one set of scores - Classic FICO. Thanks to a push to promote competition, make credit scoring more inclusive, and help more Americans become homeowners, the Federal Housing Finance Agency (FHFA) has approved the use of new credit score models such as FICO 10T and VantageScore 4.0.

A different model can mean a different number for the same person. VantageScore says its model can score about 33 million adults that the Classic FICO's model can't. So the score you saw on an app last month may not be the one your lender pulls.

Remember: the models may be new, but the basics haven't changed.

#3  Do Your Part And Partner With A Pro

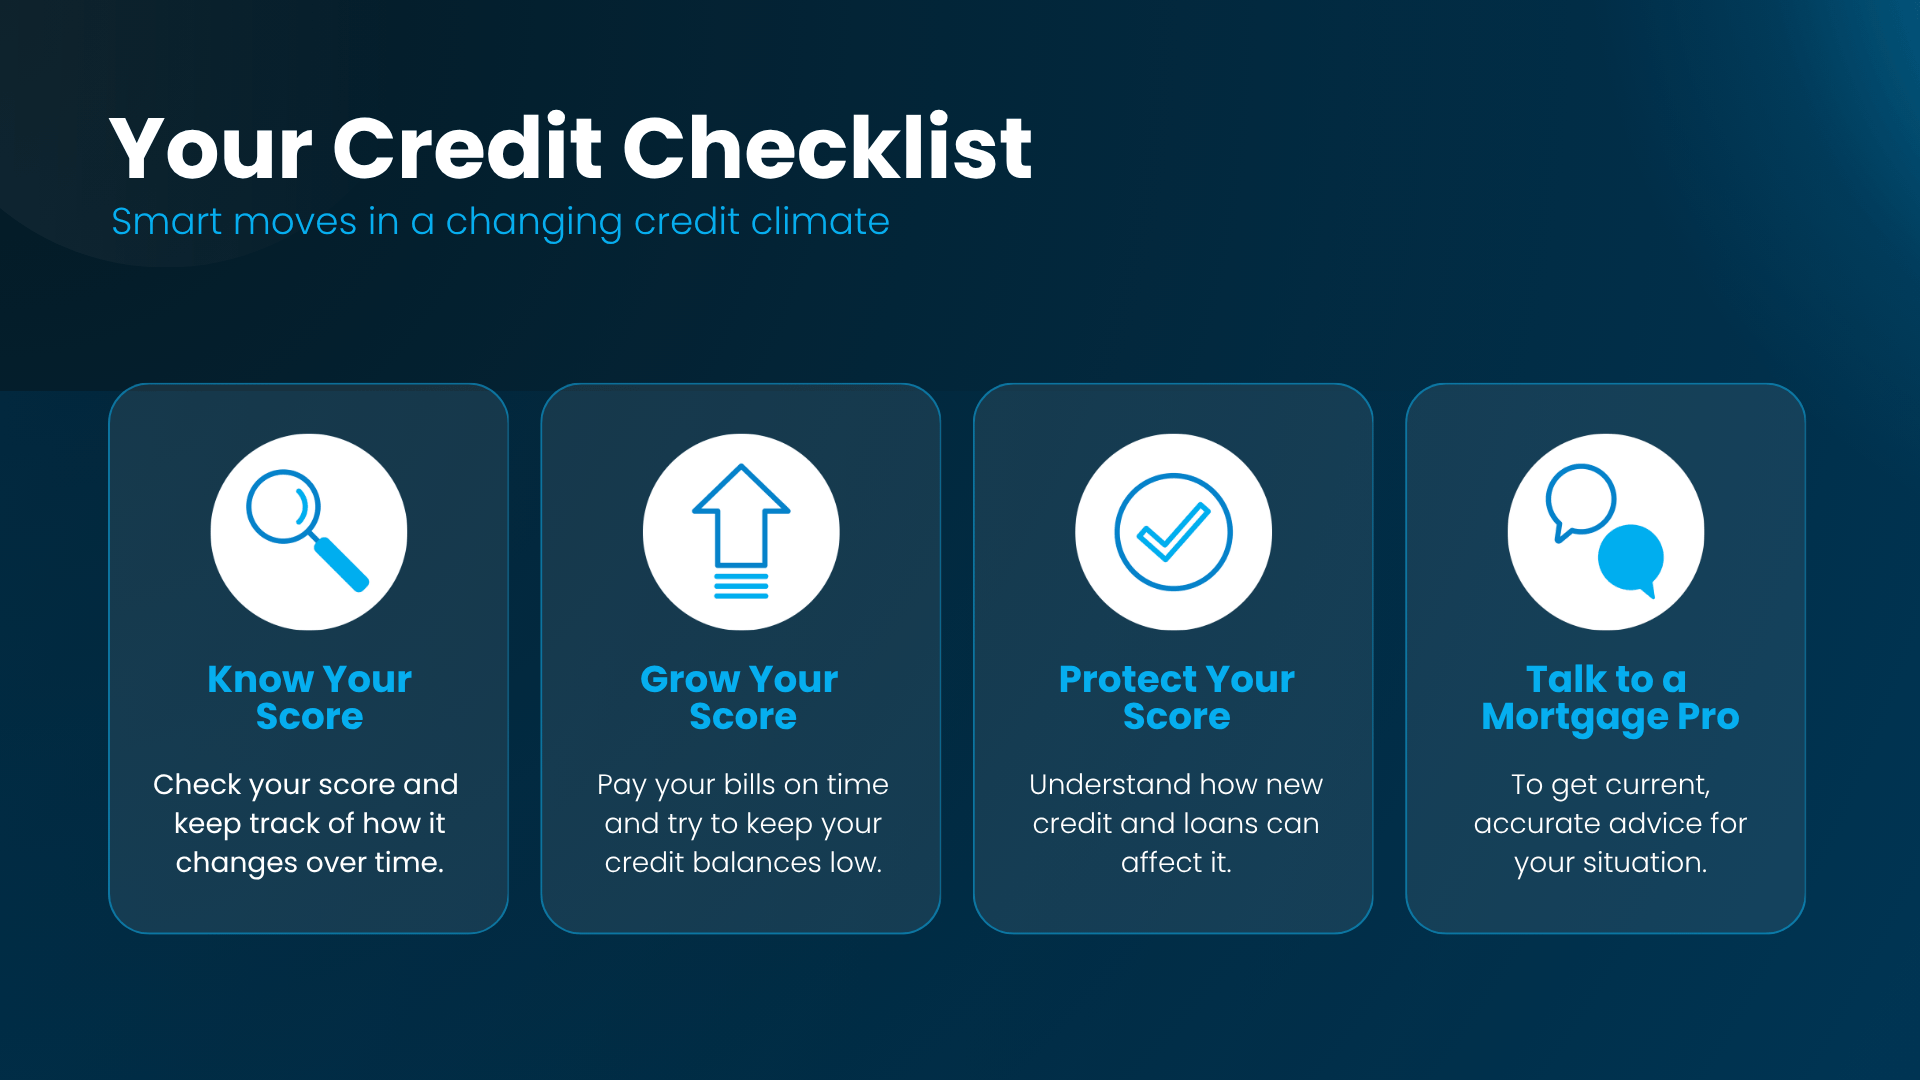
Your credit score is important - no matter how it's measured. Following the same basic rules will benefit your profile in the old and new score models:

a screen shot of a credit checklist

Because while credit models may change, the general advice for you to improve your score doesn’t. Financial awareness and consistency mixed with a little willpower can go a long way.

Bottom Line

Don't make credit or homebuying decisions from a chart, an app, or a friend's advice. With the rules shifting and so many misconceptions out there, it's never too early to talk to a professional loan officer for advice on credit, budgeting, and what it would take to qualify for a mortgage.

You may be closer to owning a home than you think.

Don't Let the Fear of a Buyer Backing Out Scare You Away from Selling


There's nothing quite like the excitement of getting an offer on your house. You're one step closer to moving on to what's next. But what happens if that buyer backs out or ghosts you before closing?

If you've been seeing headlines about more home sales falling through lately, that possibility may be keeping you up at night. And it's true. According to Redfin and Cotality, canceled contracts have been on the rise.

But here's what those headlines don't always tell you…

Most sales still go through. Only 10-15% hit this snag. And even so, there are things you can do to help keep your sale from becoming one of them.

The key is knowing what tends to scare buyers away and getting ahead of those issues before they have a chance to derail your move.

What's Behind the Rise in Canceled Contracts?

Today's buyers are being more cautious. Mortgage rates are stretching budgets, and with more homes to choose from, buyers have more freedom to walk away if something doesn't feel right. As Redfin explains:

"That gives house hunters more options and makes them more likely to walk away if an inspection uncovers problems, an appraisal comes in low or the seller doesn't agree to concessions."

That's why an accepted offer isn't always a guaranteed sale. But it doesn't mean you should be afraid to put your house on the market, either.

It just means getting ahead of potential problems matters more than ever.

3 Things That Can Scare Off a Buyer (and How To Get Ahead of Them)

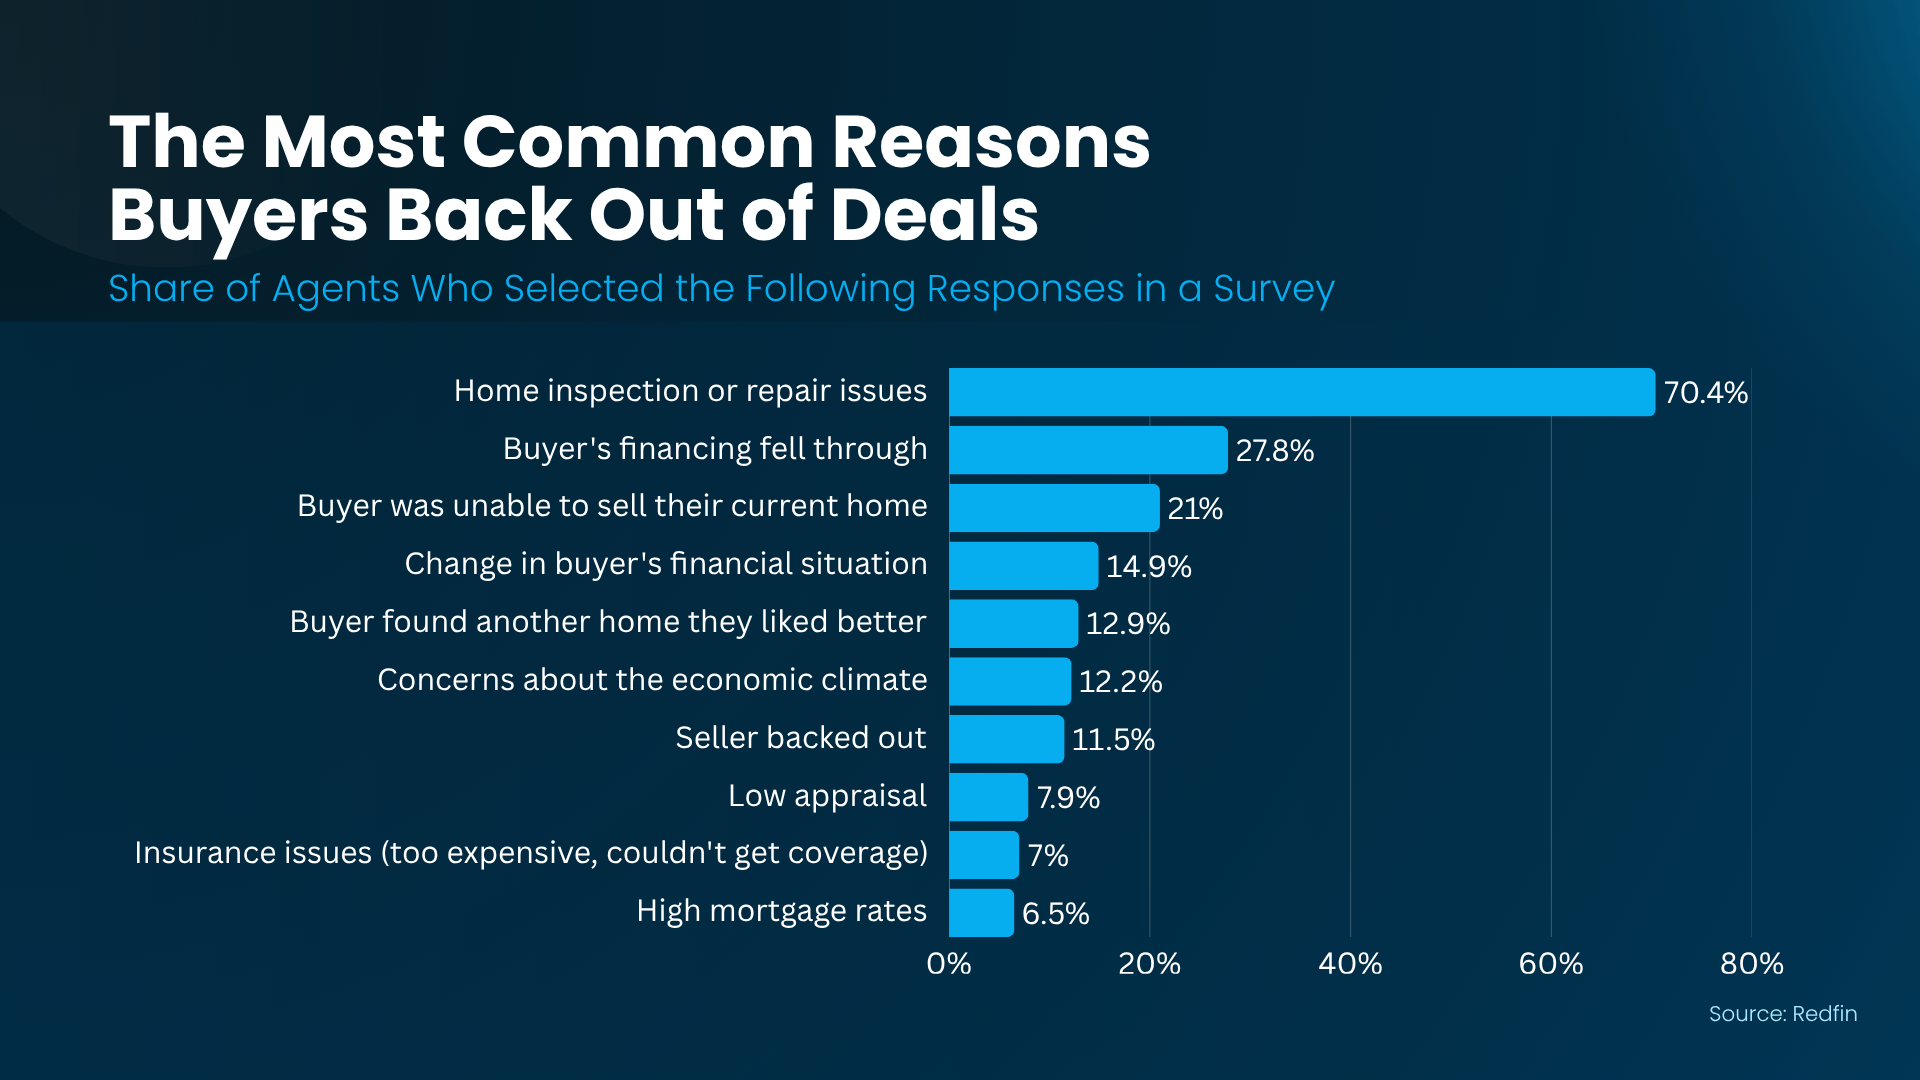
A Redfin survey asked real estate agents why some buyers are backing out. And their answers give you a short of cheatsheet into what could go sideways and how you can get ahead of those headaches (see graph below):

a graph of a survey

1. Inspection or repair issues (70.4%)

This is the big one. And the good news? It's also one of the areas where you can be the most proactive.

One simple way to head this off is by getting a pre-listing inspection before your house goes on the market. That way, if something needs attention, you can decide whether to fix it upfront (before you sell), adjust your price, or disclose it and come in already prepared for what’s likely to pop up in negotiations. It’s a lot better to find the skeletons in the closet before a buyer does.

2. Buyer financing falls through (27.8%)

Even buyers who are pre-approved can run into financing issues before closing. And with mortgage rates putting extra pressure on affordability, some buyers are finding it harder to make the numbers work.

While you can't control whether a buyer's loan goes through, you can work with your agent to look closely at their financing before accepting an offer. And if affordability is the concern, your agent can help you explore whether incentives like closing cost credits or a mortgage-rate buydown could make a difference.

3. The buyer can't sell their current home (21%)

Sometimes, your buyer needs to sell their house before they can buy yours. And if their sale falls through, yours could be affected too.

That's why it's important to understand any home-sale contingencies before accepting an offer. Your agent can help you look at where the buyer is in their own selling process and what protections you may want in place.

The goal isn't to eliminate every possible risk. It's to avoid being caught off guard by the ones you can plan for.

Don't Let the What-Ifs Keep You Up at Night 

Just remember when you read headlines about canceled deals, they don’t give you the full picture. Most home sales still make it to closing.

And if a sale does fall through, that doesn't automatically mean your house won't sell. Sometimes a buyer's circumstances change. Sometimes an issue comes up that can be addressed before the next offer.

What matters is having an agent who knows how to spot potential problems early, help you navigate negotiations, and keep your sale moving forward.

Because while you can't control every twist and turn, you can control how prepared you are.

Bottom Line

There's no need to let the fear of a buyer backing out hold you back. While no sale comes with guarantees, a little preparation upfront can go a long way toward making the whole process smoother.

If you're ready to make a move, let's talk about whether a pre-listing inspection makes sense for you.

How To Get Into a Starter Home on Mt. Hood

by Liz Warren

Two Moves That Can Get You Into Your First Home Sooner


For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.

But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.

How Long Buying Really Takes

First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

"Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting."

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.

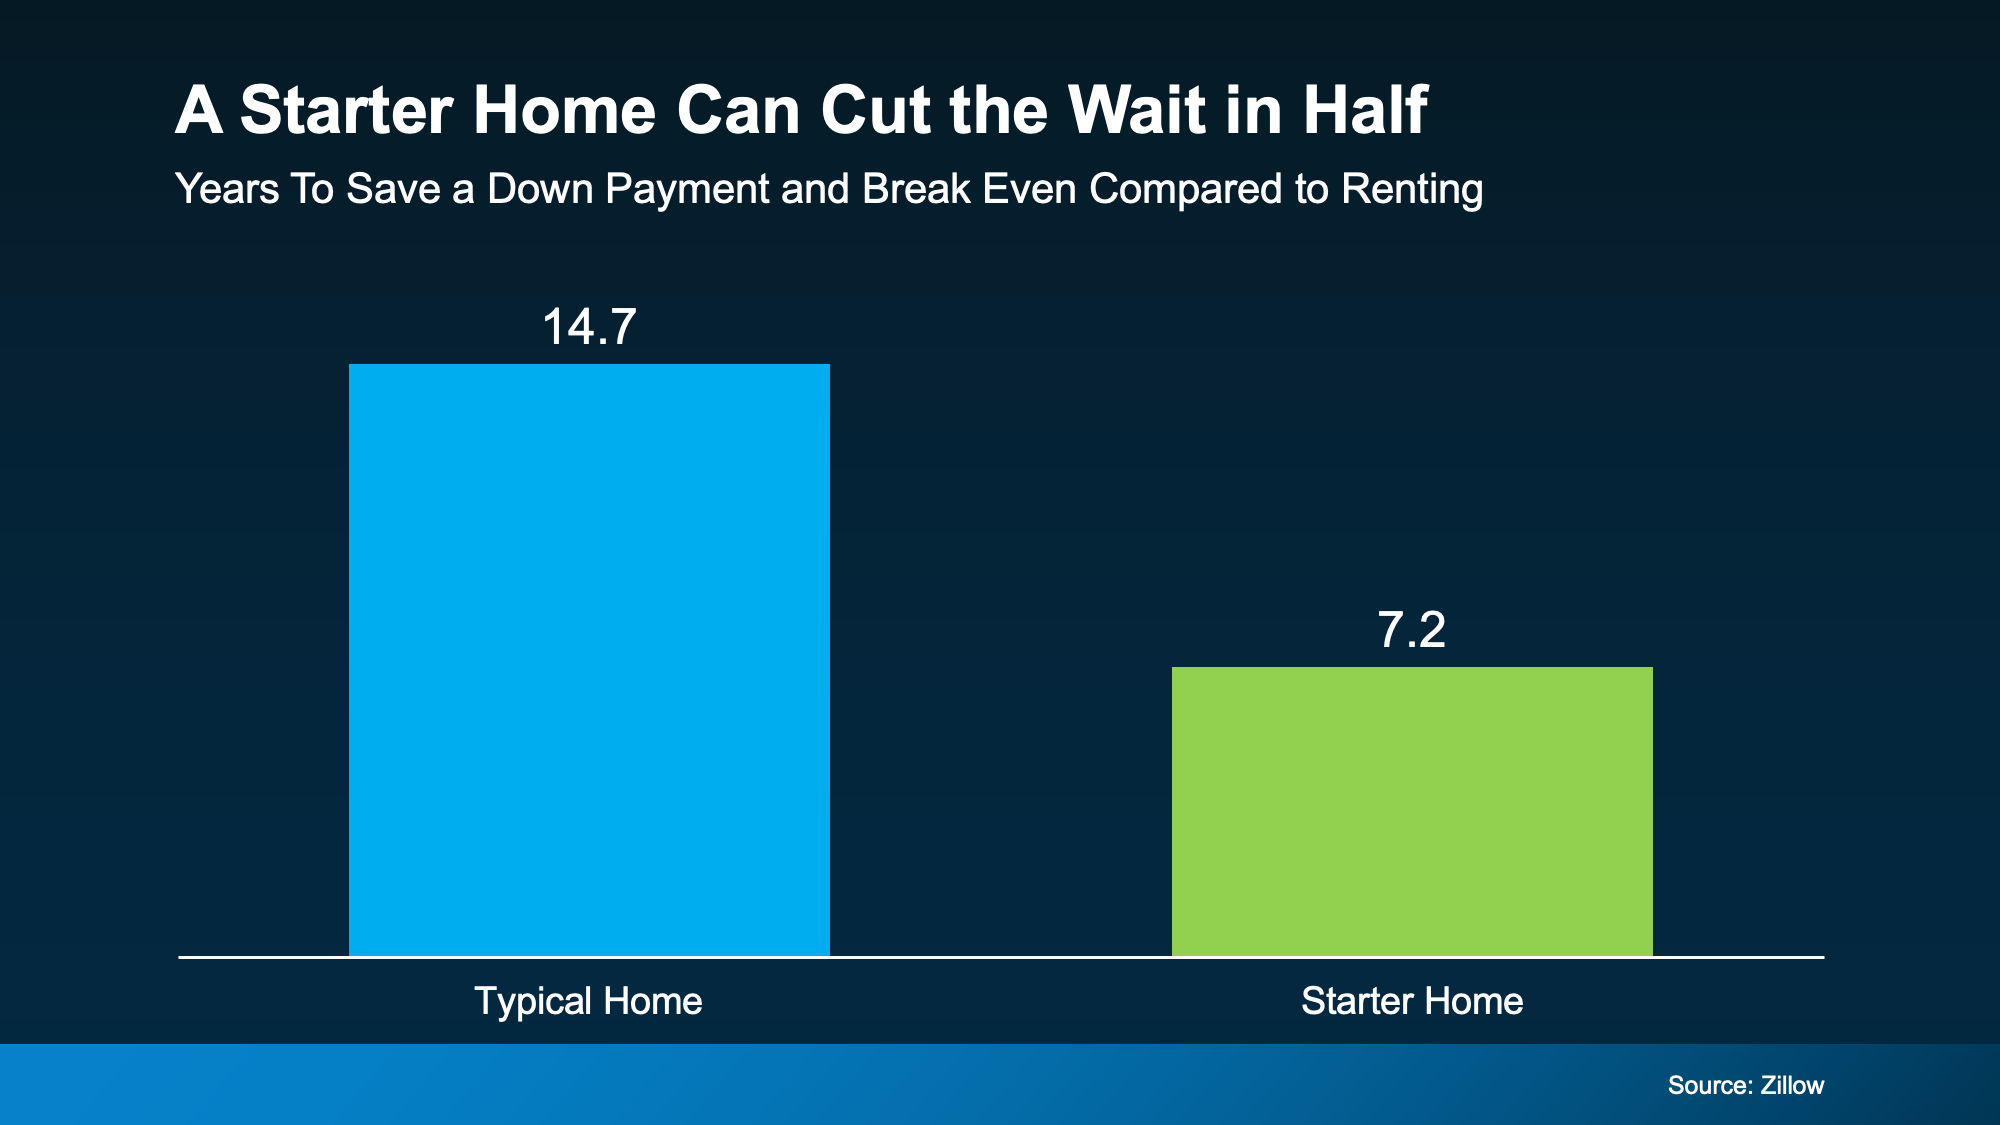
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. 

Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. 

A Starter Home Can Get You There Twice as Fast

A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. 

Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.

Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):

a graph of a number of squares

That works out to about 4.6 years to save and 2.6 years to break even. It won't erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.

You Usually Don't Need To Put 20% Down

You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. 

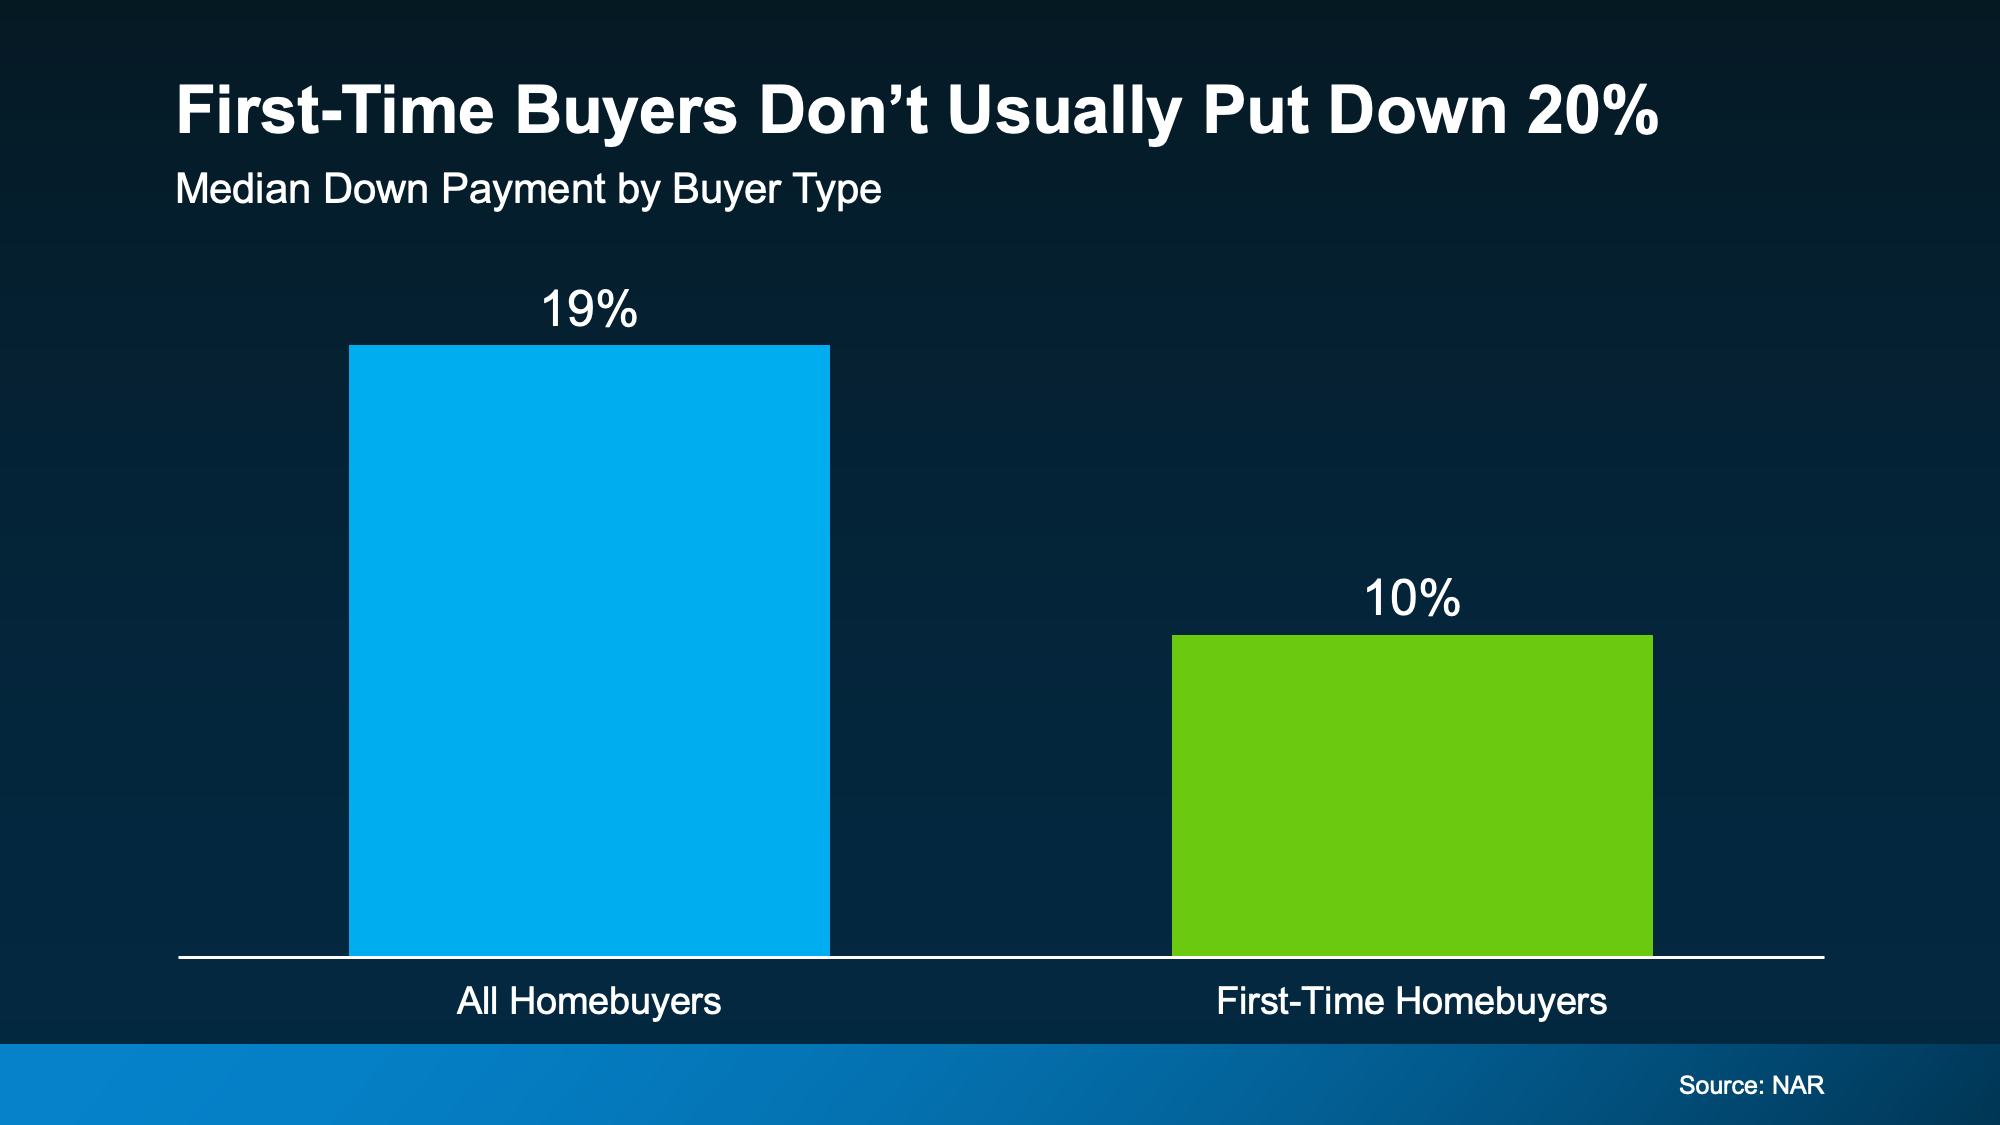
Most first-time buyers don't put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):

a graph of a sales report

And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.

There's help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

"Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase."

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.

Bottom Line

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in our area could fit your budget? Let's connect.

What Higher Mortgage Rates Mean for Home Sellers

by Liz Warren

What Higher Mortgage Rates Mean for Home Sellers


Higher mortgage rates don't just affect buyers. They can change what it takes to sell your house, too.

That's because today's buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they're looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.

If you're planning to sell, that doesn't mean you can't compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.

Builders Are Competing on the Monthly Payment

New construction has something interesting going for it right now. While existing-home sales  (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.

In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.

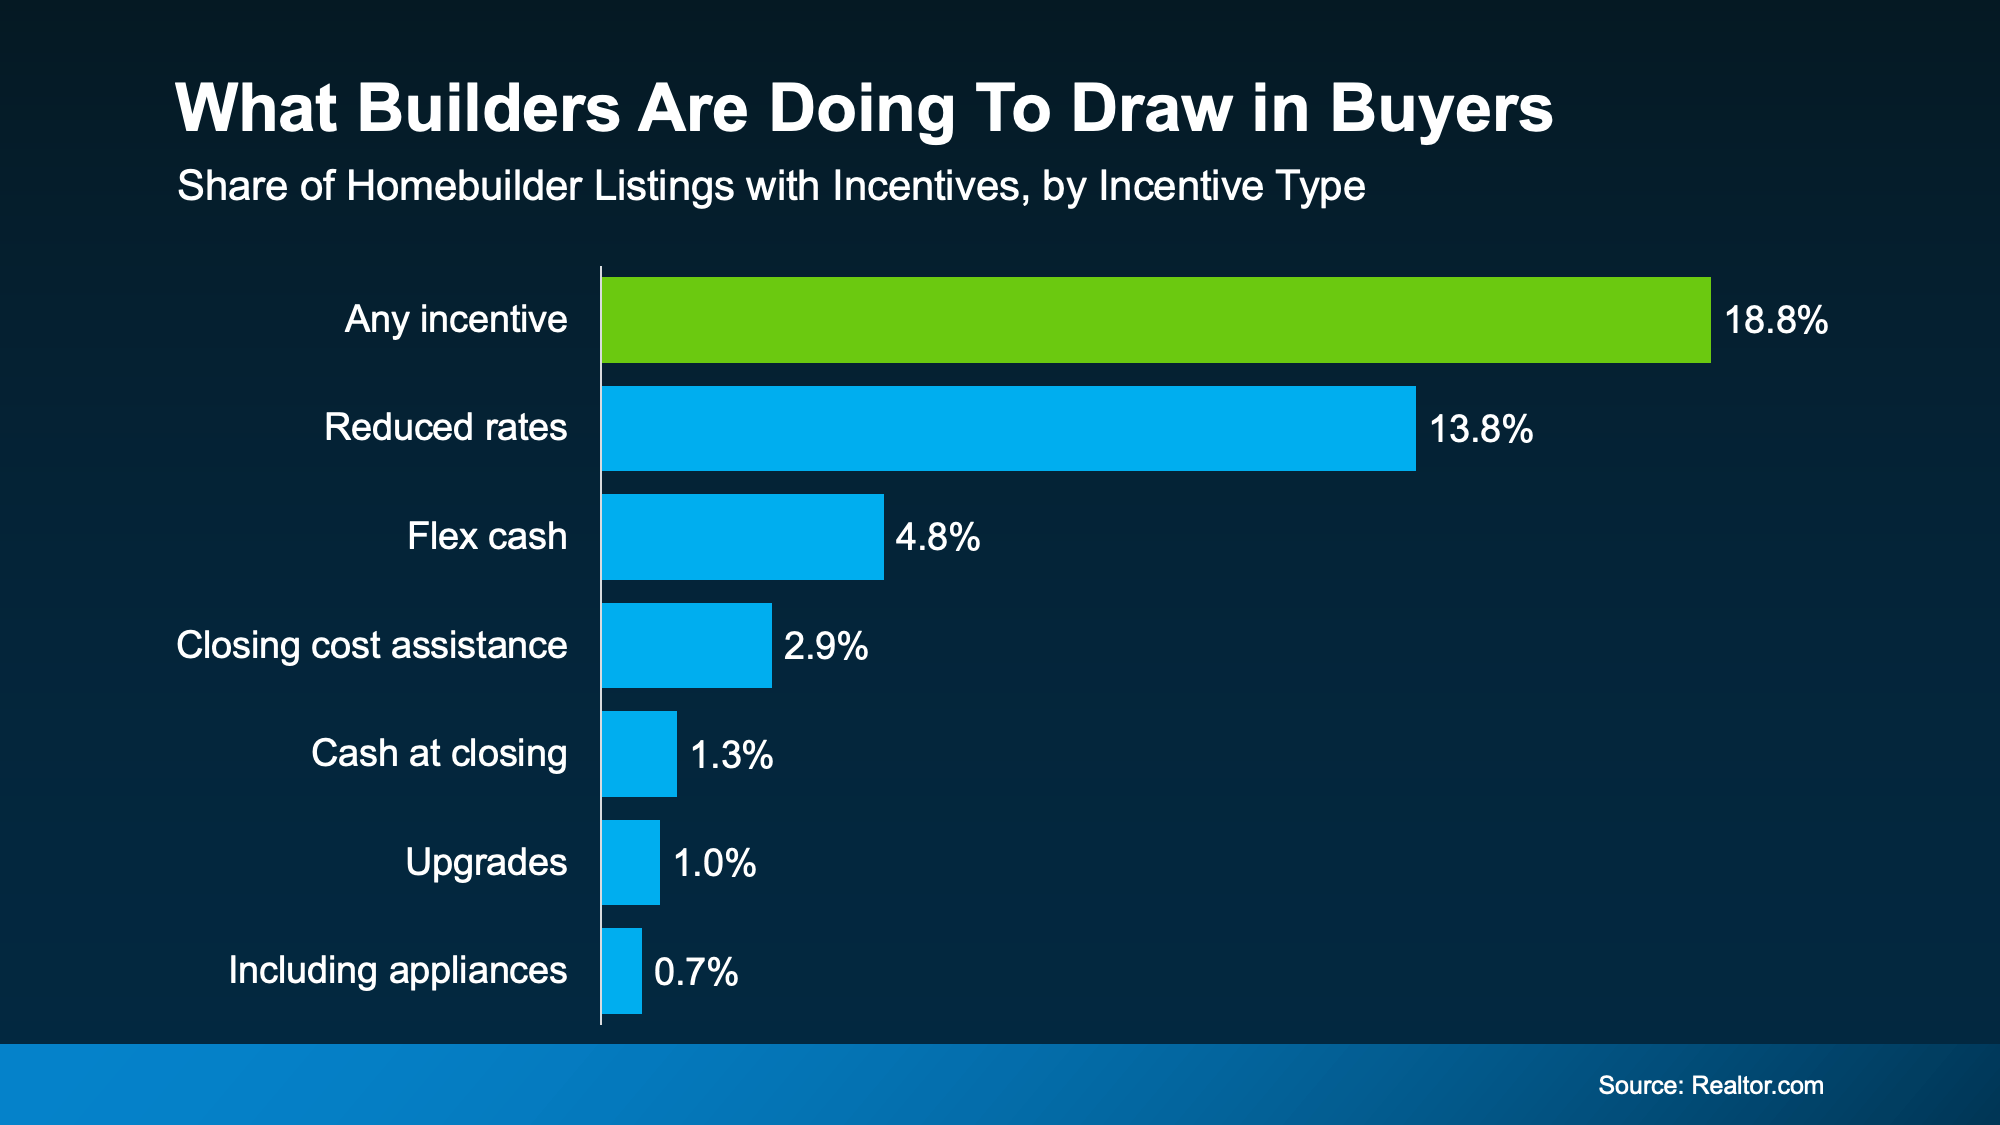
One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:

a graph of a company's sales

The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.

It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.

In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That's a big difference to a buyer who are feeling the pinch right now.

So, How Can Sellers Like You Compete?

First, don't assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer's rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.

A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can't. That's why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:

“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”

A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.

Today's Market Rewards Sellers Who Adapt

Builders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That's putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:

“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”

That's an important message if you're hoping to sell.

You don't automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.

And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren't equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.

Bottom Line

Higher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with reduced rate, closing-cost help, price reductions, and other incentives.

If you're thinking about selling, let's look at what buyers are getting from other homes in our area – including new construction – and make sure your house is positioned to compete.

Displaying blog entries 1-10 of 470

Syndication

Categories

Archives